Home Blog Page 3

Stanbic IBTC Bank PMI: Strongest Growth of Output Since February 2022

0

September data signalled strengthening growth momentum in Nigeria’s private sector as a rapid rise in new orders spurred the fastest increase in business activity since February 2022. With workloads rising, companies ramped up purchasing activity and took on extra staff, although employment rose only modestly.

Meanwhile, inflationary pressures were also marked, with companies increasing their selling prices at the fastest pace in three months in response to higher input costs.

The headline figure derived from the survey is the Purchasing Comment 24 25 26 Managers’ Index (PMI. Readings above 50.0 signal an improvement in business conditions on the previous month, while readings below 50.0 show a deterioration.

The Stanbic IBTC Bank headline PMI increased for the second month running in September to 56.4, from 54.3 in August. The latest reading signalled a marked improvement in the health of the private sector, and one that was the most pronounced in just over four and-a-half years.

A key factor behind the improvement in overall business conditions was firms’ success in securing new orders in September. Improving customer demand and the launch of new products helped lead to an eighth consecutive monthly rise in new business, and one that was the strongest since February 2022. In turn, business activity also increased at the sharpest pace since that month.

Muyiwa Oni, Head of Equity Research West Africa at Stanbic IBTC Bank commented: “Overall business conditions improved significantly in September, with the headline PMI (56.4 points vs August: 54.3 points) rising to a level not seen since February 2022 (57.3 points), thereby ensuring a better third quarter for business activities relative to the second quarter of the year.

Indeed, all the four sectors monitored by the survey recorded significant improvement in September, as firms noted improving customer demands as ensuring they secure new orders during the period while also introducing new products into the market. Based on this, companies also increased the pace of hiring although the bulk of these workers were hired on a temporary basis to complete specific tasks.

Elsewhere, higher fuel prices continue to feed into an increase in transport costs. This, in addition to increase in raw material prices, rising staff costs, as well as the prices of other food products helped to ensure that input costs maintained their uptrend. This then fed into output prices increasing to a three-month high in September.

The strong end to the quarter implies that the PMI prints in Q3:26 are consistent with a likely 4.56% y/y GDP growth in Q3:26, taking the full year 2026 growth estimate to approximately 4.4% y/y from 3.87% y/y recorded in 2025.

The non-oil sector is expected to perform better in 2026 compared to 2025 as more sectors contribute to improvement in GDP growth rate this year. Among the three broad sectors of the economy, we expect the manufacturing sector to see the biggest boost to its growth amid the low statistical base effects from 2025 while ICT, trade, real estate, and finance & insurance will likely remain the biggest drivers of the services sector’s growth.”

The latest rise in output was widespread across the different parts of the economy covered by the survey. Indeed, sector data pointed to marked expansions across all four monitored categories.

Efforts to keep on top of workloads amid sharply rising new orders led companies to expand their purchasing activity markedly in September. In some cases, inputs had been bought in anticipation of further demand improvements in the months ahead.

Higher input buying fed through to a marked accumulation of inventories, the greatest since the end of 2021. Prompt payments to suppliers reportedly ensured that items were delivered in a timely manner, and vendor performance improved for the third month running as a result.

Companies also hired additional staff in September, but the rate of job creation was only modest. Moreover, where new workers were hired, this was often only on a temporary basis to help complete specific projects. Nonetheless, the expansion in capacity during the month helped firms to keep on top of workloads despite the rapid rise in new orders.

Backlogs of work decreased for the second month running, albeit only marginally. A further sharp rise in purchase prices was recorded at the end of the third quarter, with the rate of inflation at a three-month high.

According to respondents, higher fuel costs were often behind the latest increase, while there were also reports of rising prices for animal feed, foodstuffs and other raw materials. The rate of staff cost inflation also quickened as companies helped their workers deal with higher living costs and offered incentives for completing projects on time.

Firms subsequently passed higher input prices through to customers and selling prices increased rapidly as a result. In line with the trends in purchase prices and staff costs, the latest rise in output prices was the fastest since June.

Companies were more optimistic regarding the 12-month outlook for business activity in September. Positive sentiment often reflected business expansion plans, including the opening of new branches and intentions to begin exporting products. The securing of new customers and stock-building were also factors set to support output over the coming year, according to panelists.
 

Stanbic IBTC’s AAA (nga) Rating, Unbroken for a Decade, Reaffirmed by Fitch

0

Stanbic IBTC has been reaffirmed at ‘AAA (nga)’ by Fitch Ratings, giving clients, and investors continued assurance in its financial strength and the way it is run. The affirmation extends Stanbic IBTC’s place at the top of Nigeria’s National Long-Term Rating scale for over a decade.

That span of decade included a Naira devaluation, a sharp rise in interest rates and a central bank-mandated recapitalisation exercise for Nigerian banks, each a genuine test of any institution’s balance sheet and risk controls. Stanbic IBTC’s rating has not moved through any of it.

Fitch’s stable Outlook assessment pointed to Stanbic IBTC’s comfortable liquidity coverage in both local and foreign currency, a loans-to-deposits ratio that fell to 63% in the first quarter of 2026 from 100% in 2023 as deposit growth continued to outpace lending, and operating profit that reached a record 12.8% of risk-weighted assets in the same quarter.

Its capital position also strengthened, with the Common Equity Tier 1 (CET1) ratio rising to 18.7% following a N147 billion rights issue completed in 2025. Fitch also cited the strategic backing of parent company Standard Bank Group, Africa’s largest bank by assets, which holds a 68.46% stake in Stanbic IBTC.

The effect, however, differs by audience, as clients get independent confirmation that their deposits sit with a well-managed institution. Investors get a data point that can support pricing on Stanbic IBTC’s debt and equity issuances. The market gets one more proof point that a systemically important Nigerian institution has come through a volatile decade without a single rating downgrade.

Chuma Nwokocha, Chief Executive, Stanbic IBTC Holdings, said, “A rating reflects whether an institution does what it says it will do, year after year. Holding the highest national rating from Fitch for over a decade tells us our approach to risk, governance, and how we run Stanbic IBTC has remained sound through very different economic cycles. It gives our clients and partners a clear, independent reference point as they choose who to bank with.”

Stanbic IBTC is a member of Standard Bank Group, giving it access to a pan-African network and shared governance standards, and has restated its commitment to engaging Fitch and other rating agencies as part of its regular investor disclosure process.

A&G Pitches 5-Point ‘Extra Mile’ CSW 2026 Strategy to Brokers Driven by Recapitalisation Strength

0

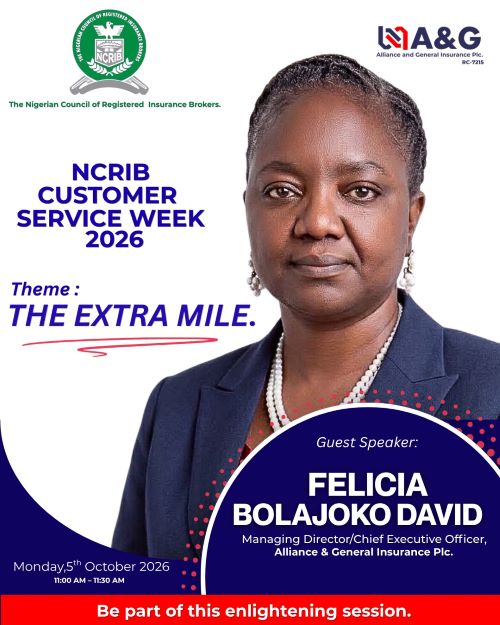
Alliance & General Insurance Plc has initiated a strategic ‘Extra Mile’ Customer Service Week (CSW) 2026 commitment to brokers in the insurance industry on the strength of its recent recapitalisation success.

Mrs. Felicia Bolajoko David, Managing Director/CEO, Alliance & General Insurance Plc stated in an address to the Nigerian Council of Registered Insurance Brokers (NCRIB) that the company is well positioned to partner the broking business community to achieve market success on the back of a five-point agenda beneficial to both parties.

She named the five-point plan as follows:

  • One: every brokerage that works with us will have a named relationship contact and a clear claims escalation path, so you never have to wonder who to call.
  • Two: you’ll hear about the progress of your client’s claim before your client does. We will not go around the broker.
  • Three: within the terms of the policy, we’ll look for a way to establish and settle a valid claim, not a reason to decline it.
  • Four: where liability is clear and the client’s business depends on it, we’ll consider interim payments rather than make clients wait for the final figure.
  • Five: your commissions will be settled promptly and transparently, because your business must grow too. I’m not asking you to take these words on trust. I’m asking you to test them. Place your next risk with Alliance & General and judge us by how we behave on the night of the fire, not by what we say on a morning like this.

The A&G CEO said the company is ready to deliver value to brokers in a symbiotic relationship, as well as to the general insuring public in the spirit of the ‘Extra Mile’ concept of CSW 2026.

In her address, she said:

“In 2026, Alliance & General completed its recapitalisation and we received our new certificate of operation from NAICOM. It means greater capacity to write larger risks, to retain more and to stand firmly behind the promises your clients are trusting you to keep. When you place a risk with A&G, you’re placing it with a company that has done the work required to meet the new standard of this industry. It requires proximity. Through our regional offices and branch network, we’re closer to your clients across the country. And it requires building for the future. We’re investing in our people, our processes and our digital capability-so that service is not dependent on one good officer on one good day, but is built into how the company works.”

She commended the Governing Board of NCRIB for the support, customer service professionals in brokerages and insurance companies alike with a promise that the week belongs to them.

Going down memory lane, she added:

“I Was One of You. Before I sat in the chair of an insurance company as CEO, I was a broker. I started my career in claims in 1992. I then spent close to two decades in broking, first at Glanvill Enthoven and later at FBN Insurance Brokers.”

Recapitalisation: The Road to Strong Capital Adequacy, Growth for Insurance Industry

0

The recent conclusion of the recapitalisation exercise in the insurance industry in Nigeria signals a sure and sustainable path towards strong capital base for insurers and remarkable market growth in the foreseeable future.

The positive scenario is also expected to deliver additional value for policyholders, businesses and the Nigerian economy going forward.

After the July 31, 2026 official deadline, the industry regulator, National Insurance Commission (NAICOM) confirmed that 48 insurance companies and two reinsurers met the new minimum capital requirements under the Nigerian Insurance Industry Reform Act (NIIRA) 2025 while six insurance licences were cancelled after the affected operators failed to meet the regulatory threshold.

Without doubt, the capital raise exercise has significantly altered the competitive structure of the insurance industry considering the infusion of about N1.079 trillion which was mobilised through the recapitalisation exercise, comprising fresh capital and existing funds that strengthened the financial position of operators.

But as the industry enters the post-recapitalisation era, questions are increasingly being raised about whether the new capital will translate into better underwriting capacity, faster claims settlement, greater domestic retention of risks and, ultimately, wider insurance coverage.

For an industry whose penetration remains below one per cent, the significance of the reform therefore extends beyond balance sheets.

The commissioner for Insurance and Chief Executive Officer of NAICOM, Olusegun Ayo Omosehin, has repeatedly stressed that recapitalisation was never intended to be an end in itself.

Omosehin emphasised that additional capital must create the capacity to underwrite larger and more complex risks, pay claims, innovate, improve customer experience and retain more risks within Nigeria. He has also identified claims payment as one of the most visible measures of the value of insurance to policyholders.

For years, the debate around insurance capacity has centred on inadequate capital, weak balance sheets and the inability of local operators to retain substantial portions of major oil and gas, aviation, marine, infrastructure and other specialised risks.

The new capital base should give insurers greater financial capacity to compete for such risks. It could also reduce excessive dependence on foreign markets and allow more insurance premiums and risk-management expertise to remain within the domestic economy.

The industry still faces a trust deficit, limited consumer awareness, affordability constraints, weak distribution networks and concerns around the speed and experience of claims settlement. These challenges are particularly important because the ultimate measure of an insurance policy for most customers is what happens when a loss occurs.

The NIA Chairman, Ebelechukwu Nwachukwu, has acknowledged this broader challenge, saying the reform should be used to strengthen market conduct, consumer confidence, innovation and the industry’s contribution to the economy.

Nwachukwu described the recapitalisation process as a foundation for stronger players with the capacity to underwrite large and complex risks, mobilise long-term capital and invest in digital transformation. She also stressed that the real test would be converting stronger balance sheets into underwriting capacity, innovation, improved claims service and wider insurance penetration.

This is particularly significant as NAICOM moves into the next phase of regulatory reform.

The commission has appointed Ernst & Young as consulting actuary for the implementation of a Risk-Based Capital (RBC) framework, which will align insurers’ capital requirements more closely with the risks inherent in their businesses.

NAICOM said the framework is intended to strengthen financial stability and policyholder protection.

The implication is that the industry may no longer be able to view the new minimum capital threshold as a permanent finish line.

Instead, insurers will increasingly be assessed on the quality and risk profile of their businesses, governance, capital adequacy, underwriting practices and ability to withstand shocks.

Industry observers also see the recapitalisation as an opportunity for insurers to invest more aggressively in technology, data, product development and alternative distribution channels.

The Chief Executive Officer (CEO) of Consolidated Hallmark Insurance, Mary Adeyanju said, stronger capital should create opportunities for greater collaboration between insurers and brokers, investment in technology and development of products that respond more closely to consumers’ needs.

For brokers, whose relationship with policyholders gives them a direct view of consumer concerns, the post-recapitalisation challenge will be to ensure that the stronger financial position of insurers translates into products that customers understand, can afford and consider valuable.

A larger capital base creates an opportunity to take on bigger risks, but it also creates pressure to generate adequate returns for shareholders who provided the funds. That could force operators to become more disciplined about underwriting, pricing, risk selection, operating costs and technology investment.

The recapitalisation has reduced the number of licensed operators and is likely to leave a more concentrated market, with stronger institutions competing for business across major corporate and retail segments. While this may create economies of scale and improve financial resilience, the industry will also need to ensure that consolidation does not weaken competition or reduce product choices for consumers.

NAICOM has already warned newly licensed operators that the next phase requires prudent utilisation of capital, stronger corporate governance, transparency and accountability.

The regulator has equally made it clear that its expectations now go beyond compliance.

The commission wants insurers to deploy the new capital towards larger risks, stronger claims-paying capacity, innovation and improved customer service while increasing the industry’s contribution to infrastructure financing and economic development.

For policyholders, therefore, the most important question after recapitalisation may be relatively simple: what changes when a claim is made?

If the answer is faster settlement, fewer disputes, better service and stronger financial protection, the reform would begin to demonstrate its value beyond the financial statements of insurance companies.

If the additional capital merely produces larger balance sheets without materially expanding coverage, improving claims experience or bringing millions of uninsured Nigerians into the formal insurance market, the broader objective of the reform would remain unfinished.

The post-recapitalisation era is consequently less about celebrating the amount of capital raised and more about converting that capital into capacity.

NAICOM has framed the next stage around stronger underwriting, claims payment, innovation, governance and consumer protection, while the NIA has called for the industry to build on the reform to deepen confidence and penetration.

With the recapitalisation hurdle now behind the industry, the harder assignment begins: turning stronger insurers into a stronger insurance market.


AXA Mansard’s New Campaign Seeks to Deepen Insurance Penetration as Path to Economic Growth

0

AXA Mansard Insurance Plc has unveiled a new strategic effort aimed at deepening insurance penetration in Nigeria.

The company is positioning protection not only as a financial safeguard for individuals and businesses but also as a critical driver of economic resilience and long-term national growth.

Speaking at the launch of the company’s new pan-African ‘Culture of Care’ campaign, Chief Executive Officer of AXA Mansard Insurance Plc, Kunle Ahmed, said the initiative reflects the company’s commitment to helping more Nigerians understand the role protection plays in securing livelihoods, strengthening businesses, and building a more resilient economy.

The campaign is built around the idea that care and protection are deeply connected, and that insurance is one of the most practical ways to translate care into long-term security.

According to Ahmed, broadening access to insurance is an important step toward closing Nigeria’s protection gap and unlocking greater economic confidence.

“Every day, Nigerians demonstrate a culture of care through the sacrifices they make for their families, employees, customers, and communities. Insurance is an extension of that care because it helps protect what people have worked hard to build,” he said.

“Insurance is economic infrastructure. It helps families recover from setbacks, gives businesses the confidence to invest and grow, and supports economic stability by enabling people to plan for the future with greater certainty,” he added.

The Culture of Care campaign seeks to reframe conversations around insurance by connecting protection to values Nigerians already understand and practise. By encouraging a stronger appreciation for the role of protection in everyday life, AXA Mansard hopes to contribute to increased insurance adoption across households, small businesses, and larger enterprises.

For businesses, stronger insurance uptake translates into improved resilience against operational disruptions, unforeseen losses, and emerging risks. For households, it reduces financial vulnerability and helps preserve hard-earned savings when unexpected events occur. According to Ahmed, these benefits ultimately extend beyond individual policyholders to the wider economy.

“As Nigeria pursues greater economic transformation, we must build institutions and systems that make individuals, families, and businesses more resilient. Protection gives people confidence. Confidence encourages investment. Investment drives growth,” he said.

The CEO also highlighted the significance of ongoing reforms within the insurance industry, noting that a stronger and more trusted insurance sector can play an increasingly important role in supporting entrepreneurship, attracting investment, and facilitating sustainable economic development.

At the heart of the campaign is AXA’s belief that protection should be viewed not merely as a response to risk, but as an enabler of progress. By encouraging more Nigerians to embrace protection as part of everyday financial planning, the company believes the insurance industry can make a stronger contribution to the country’s development aspirations.

“Building a prosperous nation requires more than ambition. It requires confidence, resilience, and the ability to withstand uncertainty,” Ahmed said. “Through the Culture of Care, we are helping to promote a mindset that values protection as a foundation for progress. Stronger protection creates stronger families, stronger businesses, and ultimately a stronger economy.”

The campaign forms part of AXA Mansard’s broader commitment to advancing financial inclusion, expanding protection and contributing to the development of a more resilient and prosperous Nigeria.

AXA Mansard Investment: Financial Security is Critical to Long-Term Prosperity

0

AXA Mansard Investment Limited has highlighted the critical role of financial security in helping individuals, families and communities build resilience, calling for greater focus on long-term financial wellbeing as a key component of sustainable economic development.

Speaking at the unveiling of AXA’s Culture of Care campaign, Chief Executive Officer of AXA Mansard Investment Limited, Deji Tunde-Anjous, said the campaign reflects a broader conversation about what it truly means to care for people, not only in the present, but also in the future. According to him, care is often expressed through sacrifice and support, but one of its most enduring expressions is helping people achieve financial security and peace of mind.

“Financial security is one of the most powerful forms of protection,” said Tunde-Anjous. “It allows people to face uncertainty with greater confidence, pursue opportunities with courage, and build futures that are not defined by fear or vulnerability.”

He noted that while care is deeply embedded in Nigerian society, many individuals devote significant time and resources to supporting others while overlooking their own long-term financial wellbeing. Parents invest in their children’s futures, entrepreneurs create opportunities for employees, and professionals provide support for extended family members and dependents. These everyday acts of responsibility are a reflection of care, but they also underscore the need for stronger financial preparedness.

According to him, the Culture of Care campaign aims to encourage a broader understanding of protection, one that extends beyond immediate needs to include long-term financial resilience.

“Saving, investing, planning for retirement, building wealth, and preparing for future responsibilities are all acts of care,” he said. “They are ways people protect not only themselves, but also the people who depend on them.”

Tunde-Anjous explained that financially secure households are better positioned to weather economic disruptions, invest in education, pursue entrepreneurial opportunities, and contribute productively to national development. As more people build financial resilience, communities become stronger and economic growth becomes more sustainable.

He described financial well-being as an often-overlooked foundation of prosperity, stressing that economic progress is strongest when individuals and families have the confidence to plan beyond immediate challenges.

“A prosperous nation is built on financially secure people,” he said. “When individuals have the tools and confidence to prepare for the future, they make better decisions, seize opportunities and contribute more meaningfully to economic growth.”

The AXA Culture of Care campaign is built on the premise that protection takes many forms. While healthcare and insurance remain essential pillars of protection, financial security plays an equally important role in enabling people to thrive, preserve wealth, and pursue their aspirations with confidence.

For AXA Mansard Investment, this means helping individuals transform today’s earnings into tomorrow’s opportunities through disciplined investing, wealth preservation, and long-term financial planning. However, Tunde-Anjous emphasised that the campaign’s broader objective is not about products, but about fostering a mindset that values preparation, responsibility, and resilience.

“The deepest expression of care is ensuring that the people we love, and the futures we are building, remain protected long after today’s challenges have passed,” he said. “When more Nigerians are financially secure, families become stronger, communities become more resilient, and the nation becomes more prosperous.”

Through the Culture of Care campaign, AXA Mansard Investment is reinforcing its commitment to advancing financial wellbeing and encouraging more Nigerians to see financial planning as an act of care for themselves, their families, and future generations.


Customer Service Week: PalmPay Goes the Extra Mile to Keep Customers Supported and Secure

0

PalmPay is celebrating Customer Service Week 2026 by highlighting its commitment to delivering a reliable and secure banking experience for its customers. With this year’s theme, “The Extra Mile,” PalmPay is reinforcing its approach to customer service that goes beyond resolving enquiries.

For PalmPay, going the extra mile means anticipating where customers may need support, strengthening the tools that protect them and making it easier to get help when something goes wrong.

This approach is reflected in PalmPay Dey For You, the company’s ongoing commitment to customer protection, which brings together security awareness, proactive protection and tools designed to help customers manage their accounts with confidence.

For millions of Nigerians, PalmPay has become a go-to digital banking platform for everyday transactions. In an evolving digital environment like Nigeria, reliability means more than a successful transaction. It also means having the right security tools and knowing that the right support is available when a customer has a concern about their account.

As part of this commitment to customer support, PalmPay introduced its Transaction Dispute Page as part of the tools launched alongside its bespoke security campaign “PalmPay Dey For You”, giving customers a dedicated channel to report and track transaction-related concerns through the resolution process.

Speaking on the company’s commitment to going the extra mile, Femi Hanson, Head of Marketing, PalmPay Nigeria said, “PalmPay’s customer service remains an important part of the banking experience, providing customers with the support they need with their accounts. Our approach is built around more than resolving complaints, it is about being present when customers need us most and making sure that every customer who reaches out feels supported and prioritised.”

Alongside customer support, PalmPay continues to equip customers with security tools including Night Guard, Large Transaction Shield, USSD Account Lock, among others, designed to provide extra protection across different transaction scenarios.

Together, these tools, processes and the people behind them reflect PalmPay’s commitment to going the extra mile; helping customers stay protected, informed and supported throughout their banking journey.

While Customer Service Week provides an opportunity to spotlight PalmPay’s 24/7 availability, the company is also celebrating the broader measures it has put in place to strengthen customer protection, improve support and build trust in its digital banking experience.


NLNG Promotes AI Innovation to Improve Medical Imaging in Nigeria

0

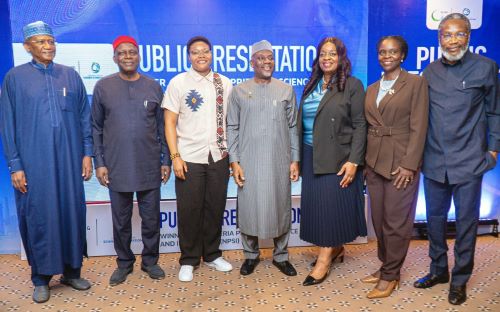
L-R: Prof. Yusuf Abubakar, Member, Advisory Board of NPSI; Prof Barth Nnaji, Chairman, Advisory Board of NPSI; Miss Mary-Brenda Akoda, winner, NPSI 2026; Dr. Maruf Alausa, Education Minister; Dr. Sophia Horsfall, GM, External Relations, NLNG; Anne-Marie Palmer-Ikuku, Manager, Corporate Communication, NLNG and Prof Adesoji Adesugba, Deputy President, Abuja Chamber of Commerce at the public presentation of the winner of the NPSI at Abuja.

Nigeria LNG Limited (NLNG) has presented GenScan AI, the winning work of The Nigeria Prize for Science and Innovation (NPSI) 2026 to stakeholders in Abuja highlighting its potential to accelerate magnetic resonance imaging (MRI) and improve access to diagnostic services.

Developed by Mary-Brenda Akoda, GenScan AI uses artificial intelligence to shorten MRI scan times while maintaining or improving image quality. The presentation brought together stakeholders to explore its potential application in Nigeria’s health sector and the steps required to translate the research into clinical use.

According to the Advisory Board of NPSI, who declared the prize winner, “its C-MORE algorithm uses a one-step framework to reconstruct MRI images, with the potential to reduce scan acquisition times by up to 90 per cent without requiring new MRI hardware.”

By shortening scan times, the technology could enable healthcare providers to attend to more patients, reduce waiting times and make better use of existing MRI equipment. These potential benefits informed the recognition of its relevance to healthcare delivery.

In her welcome remarks, Sophia Horsfall, NLNG’s General Manager, External Relations and Sustainable Development, emphasised the importance of accurate diagnosis to effective treatment. She noted that diagnostic imaging provides evidence that helps medical teams identify conditions and make informed decisions about patient care.

“Our interest goes beyond recognising an outstanding idea. We want to see scientific research make a practical difference in people’s lives. GenScan AI offers the prospect of faster medical imaging and better use of existing equipment. This presentation creates an opportunity to discuss what is needed to move that promise towards practical application.”

Speaking on the winning entry, Professor Barth Nnaji, the Prize’s Advisory Board, said the winning work stood out for the strength of its science and its potential to address a practical healthcare need.

He identified engagement with clinicians and other stakeholders as the next step in assessing how the technology could be used safely and effectively. The presentation, he added, offered an opportunity to examine its potential and the requirements for further development and application.

Akoda emerged as the 2026 winner from a record 237 entries submitted under the theme, “Innovations in Artificial Intelligence, ICT and Digital Technologies for Development”. Her selection followed an independent evaluation by the Panel of Judges, chaired by Dr Omobola Johnson, and endorsement by the Advisory Board.

She is the first woman and the first millennial to win the Prize as an individual recipient and is scheduled to receive the US$100,000 award at the Grand Award Night on 9 October 2026.

Sponsored by NLNG, The Nigeria Prize for Science and Innovation recognises excellence in scientific research and promotes innovations that address practical challenges. The public presentation advances this objective by connecting winning research with institutions and professionals who can help translate its potential into tangible benefits for society.


Heirs Gen Ins CEO, Fayemi: Customers Judge Insurance by Claims, Not Promises

0

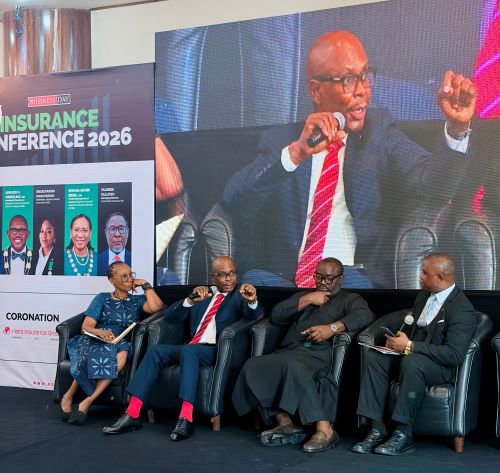
L-R: Dr. Abimbola Tiamiyu, Registrar, CIIN; Wole Fayemi, Managing Director/CEO, Heirs General Insurance; Dr. Osinowo Ibrahim, CEO, Moriahrick International & Risk Consulting Limited and Terry Ferdinand, Founder and Managing Partner, Camferd Partners Nigeria Limited during a panel session at the BusinessDay Insurance Conference.

“Customers do not judge insurance by promises; they judge it by claims. Every claim paid is an opportunity to build trust.”

Wole Fayemi, Managing Director/CEO of Heirs General Insurance, has challenged insurers to rebuild public confidence and deepen insurance penetration through prompt claims payment, customer-focused innovation and easier access to insurance solutions.

Fayemi joined other leading voices in Nigeria’s insurance industry for the panel session, “Driving Insurance Penetration: Innovation, Distribution & Customer Trust”, at the BusinessDay Insurance Conference held on September 23, where he helped shape the conversation on practical strategies for accelerating insurance adoption across the country.

According to Fayemi, the industry’s growth ambitions will depend not only on stronger capital positions but also on its ability to consistently deliver on its promise to customers.

“Customers must be confident that insurers will fulfil their promises when it matters most. Trust is fundamental to the insurance proposition, and it is earned through action, not messaging. Every claim settled promptly, every commitment honoured and every positive customer experience strengthens confidence in the industry”

He cited Heirs Insurance Group’s claims performance as evidence of the role claims fulfilment plays in building credibility and encouraging wider adoption of insurance.

“At Heirs Insurance Group, we have remained committed to delivering on our promise to customers. In 2025 alone, our companies paid ₦19.4 billion in claims, with seven out of every ten claims settled within 48 hours. We believe the most effective way to build confidence in insurance is by ensuring customers experience its value first-hand”.

He also highlighted the Group’s investments in digital innovation as creating moments for customer value. Such initiatives include the SimpleLife App, USSD services for customers without smartphones, and PrinceAI, its multilingual AI-powered assistant that enables customers to interact with the company in their preferred language.

Fayemi further noted that the successful recapitalisation of the insurance industry presents a unique opportunity to translate stronger capital capacity into meaningful value for customers. However, sustainable growth will not be driven by capital alone, but by the industry’s ability to innovate, expand access and develop solutions that address the realities of everyday Nigerians.

The BusinessDay Insurance Conference 2026, themed “From Capital to Capacity: Driving Innovation and Trust in Nigeria’s Insurance Sector,” brought together key stakeholders across the insurance ecosystem to discuss strategies for strengthening customer confidence, broadening distribution and accelerating industry growth.


About Heirs Insurance Group

Heirs Insurance Group is the insurance arm of Heirs Holdings, the leading pan-African investment company, with investments across 24 countries and four continents.

With a rapidly expanding retail footprint and an omnichannel digital presence, Heirs Insurance Group, comprising Heirs General Insurance Limited, Heirs Life Assurance Limited, and Heirs Insurance Brokers, serves both corporate and individual customers across Nigeria.

Heirs Insurance Group is championing financial inclusion and leading the digital insurance play in Nigeria, demonstrating its mission to democratise access to insurance.


Stanbic IBTC Bank PMI: Strongest Growth of Output Since February 2022

0

September data signalled strengthening growth momentum in Nigeria’s private sector as a rapid rise in new orders spurred the fastest increase in business activity since February 2022. With workloads rising, companies ramped up purchasing activity and took on extra staff, although employment rose only modestly.

Meanwhile, inflationary pressures were also marked, with companies increasing their selling prices at the fastest pace in three months in response to higher input costs.

The headline figure derived from the survey is the Purchasing Comment 24 25 26 Managers’ Index (PMI. Readings above 50.0 signal an improvement in business conditions on the previous month, while readings below 50.0 show a deterioration.

The Stanbic IBTC Bank headline PMI increased for the second month running in September to 56.4, from 54.3 in August. The latest reading signalled a marked improvement in the health of the private sector, and one that was the most pronounced in just over four and-a-half years.

A key factor behind the improvement in overall business conditions was firms’ success in securing new orders in September. Improving customer demand and the launch of new products helped lead to an eighth consecutive monthly rise in new business, and one that was the strongest since February 2022. In turn, business activity also increased at the sharpest pace since that month.

Muyiwa Oni, Head of Equity Research West Africa at Stanbic IBTC Bank commented: “Overall business conditions improved significantly in September, with the headline PMI (56.4 points vs August: 54.3 points) rising to a level not seen since February 2022 (57.3 points), thereby ensuring a better third quarter for business activities relative to the second quarter of the year.

Indeed, all the four sectors monitored by the survey recorded significant improvement in September, as firms noted improving customer demands as ensuring they secure new orders during the period while also introducing new products into the market. Based on this, companies also increased the pace of hiring although the bulk of these workers were hired on a temporary basis to complete specific tasks.

Elsewhere, higher fuel prices continue to feed into an increase in transport costs. This, in addition to increase in raw material prices, rising staff costs, as well as the prices of other food products helped to ensure that input costs maintained their uptrend. This then fed into output prices increasing to a three-month high in September.

The strong end to the quarter implies that the PMI prints in Q3:26 are consistent with a likely 4.56% y/y GDP growth in Q3:26, taking the full year 2026 growth estimate to approximately 4.4% y/y from 3.87% y/y recorded in 2025.

The non-oil sector is expected to perform better in 2026 compared to 2025 as more sectors contribute to improvement in GDP growth rate this year. Among the three broad sectors of the economy, we expect the manufacturing sector to see the biggest boost to its growth amid the low statistical base effects from 2025 while ICT, trade, real estate, and finance & insurance will likely remain the biggest drivers of the services sector’s growth.”

The latest rise in output was widespread across the different parts of the economy covered by the survey. Indeed, sector data pointed to marked expansions across all four monitored categories.

Efforts to keep on top of workloads amid sharply rising new orders led companies to expand their purchasing activity markedly in September. In some cases, inputs had been bought in anticipation of further demand improvements in the months ahead.

Higher input buying fed through to a marked accumulation of inventories, the greatest since the end of 2021. Prompt payments to suppliers reportedly ensured that items were delivered in a timely manner, and vendor performance improved for the third month running as a result.

Companies also hired additional staff in September, but the rate of job creation was only modest. Moreover, where new workers were hired, this was often only on a temporary basis to help complete specific projects. Nonetheless, the expansion in capacity during the month helped firms to keep on top of workloads despite the rapid rise in new orders.

Backlogs of work decreased for the second month running, albeit only marginally. A further sharp rise in purchase prices was recorded at the end of the third quarter, with the rate of inflation at a three-month high.

According to respondents, higher fuel costs were often behind the latest increase, while there were also reports of rising prices for animal feed, foodstuffs and other raw materials. The rate of staff cost inflation also quickened as companies helped their workers deal with higher living costs and offered incentives for completing projects on time.

Firms subsequently passed higher input prices through to customers and selling prices increased rapidly as a result. In line with the trends in purchase prices and staff costs, the latest rise in output prices was the fastest since June.

Companies were more optimistic regarding the 12-month outlook for business activity in September. Positive sentiment often reflected business expansion plans, including the opening of new branches and intentions to begin exporting products. The securing of new customers and stock-building were also factors set to support output over the coming year, according to panelists.
Sovereign Trust Insurance: Advancing Extra Mile as a Lifestyle in CSW 2026

0

As the world marks Customer Service Week 2026, Sovereign Trust Insurance Plc has reaffirmed its commitment to delivering exceptional service and creating meaningful experiences for its customers, in line with this year’s theme, “The Extra Mile.”

Commenting on the significance of the week, the Managing Director/Chief Executive Officer of Sovereign Trust Insurance Plc, Mr. Lucas Durojaiye, said that going the extra mile is more than simply meeting expectations; it is about demonstrating genuine commitment to customers at every point of their journey.

“At Sovereign Trust Insurance, we believe that excellent customer service is not a one-time effort. It is a commitment that must be reflected in every interaction, every response, and every solution we provide. Going the extra mile means listening more closely, responding more promptly, understanding our customers’ needs and doing what we can to make their experience with us better,” he said.

The MD noted that in the insurance industry, where trust and reliability are fundamental, customer service plays a critical role in building lasting relationships. He added that the Company remains focused on leveraging its people, processes and technology to make insurance simpler, more responsive and more accessible to its customers.

He further appreciated Sovereign Trust Insurance customers for their continued confidence and patronage, while encouraging employees to remain intentional about creating positive experiences.

“Our customers are at the heart of what we do, and this year’s theme is a timely reminder that every member of our team has a role to play in delivering on our promise. The extra mile may sometimes be a small gesture, a timely response or simply taking the time to understand a customer’s concern. But those moments matter, and they are what build trust,” he added.

As part of its Customer Service Week activities, Sovereign Trust Insurance is celebrating its employees and reinforcing the importance of a customer-first culture across its branches and business operations.

The company remains committed to providing innovative insurance solutions and service experiences that protect what matters most to its customers while strengthening its position as a trusted partner in their financial and personal journeys.


Excellent Leaders Secondary School Emerges Best at Tech Spark 2026

0

The first-prize winning team of Excellent Leaders Secondary School, Lagos (middle) and the first and second runners-up at the Tech Spark 2026 in Lagos recently.

Excellent Leaders Secondary School, Iju-Ishaga, Lagos has clinched the first prize in the just-concluded secondary school technology competition tagged Tech Spark 2026, held on Friday, October 2 at the MUSON Centre, Lagos.

The school emerged the best after a series of intense knockout stages in the Bug Bounty Challenge, beating Dansol High School, Lagos and Mountain Top Secondary School, Lagos owned by the Mountain of Fire and Miracles Ministries.

In his remarks, the elated Proprietor of the top-class school, Dr. Davidson Faleye said: “Excellent Leaders is truly blessed with tech-savvy, brilliant and exceptionally talented students, with so many more waiting for opportunities to shine and demonstrate what they can do. Representing us in this competition are Felix Saviour (who led the team), Abiodun Oreoluwa, Ogunseitan Oluwaseun, Rabiu Desire, Eko Olamide, Oyakeye Jessica and Oriyomi Aminat.”

Faleye expressed special appreciation to Mr. Ajewole Michael, the ICT teacher of the school for his dedication, guidance and coordination of the victorious school team.

“We will not relent in identifying, developing, celebrating and projecting the incredible talents of Excellent Leaders students to the world at every given opportunity. This victory is yet another reminder that when our students are given the platform, they can rise, compete and excel! Congratulations, Excellent Leaders!” the Proprietor emphasised.


Excellent Leaders Secondary School Emerges Best at Tech Spark 2026

0

The first-prize winning team of Excellent Leaders Secondary School, Lagos (middle) and the first and second runners-up at the Tech Spark 2026 in Lagos recently

Excellent Leaders Secondary School, Iju-Ishaga, Lagos has clinched the first prize in the just-concluded secondary school technology competition tagged Tech Spark 2026, held on Friday, October 2 at the MUSON Centre, Lagos.

The school emerged the best after a series of intense knockout stages in the Bug Bounty Challenge, beating Dansol High School, Lagos and Mountain Top Secondary School, Lagos owned by the Mountain of Fire and Miracles Ministries.

In his remarks, the elated Proprietor of the top-class school, Dr. Davidson Faleye said: “Excellent Leaders is truly blessed with tech-savvy, brilliant and exceptionally talented students, with so many more waiting for opportunities to shine and demonstrate what they can do. Representing us in this competition are Felix Saviour (who led the team), Abiodun Oreoluwa, Ogunseitan Oluwaseun, Rabiu Desire, Eko Olamide, Oyakeye Jessica and Oriyomi Aminat.”

Faleye expressed special appreciation to Mr. Ajewole Michael, the ICT teacher of the school for his dedication, guidance and coordination of the victorious school team.

“We will not relent in identifying, developing, celebrating and projecting the incredible talents of Excellent Leaders students to the world at every given opportunity. This victory is yet another reminder that when our students are given the platform, they can rise, compete and excel! Congratulations, Excellent Leaders!” the Proprietor emphasised.

NAIPE Confab 2026: 28 Insurance, Pension Stakeholders Show Support as Event Kickstarts 12noon on Thursday

0

About 28 insurance and pension regulators and operators have provided corporate partnership and support towards the upcoming 11th edition of the Nigerian Association of Insurance and Pension Editors (NAIPE) Annual Conference scheduled to hold in Lagos.

This is even as the timing of the event scheduled to hold on Thursday, October 8, 2026 at Oriental Hotel, Victoria Island, Lagos, has been shifted from 9:00am to 12:00pm same day.

This is to allow insurance operators, who will be attending Insurers Committee meeting earlier that day, conclude their meeting and attend the conference.

The national conference with a focus on the emerging market dynamics in Nigeria’s insurance and pension sectors, followed the just concluded recapitalisation exercise in the insurance sector and ongoing exercise in the pension industry.

Themed: “Post-Recapitalisation and Market Dynamics in Insurance & Pension Sectors,’ the Chief Executive Officer of United Capital Asset Management Limited, Dr. Odiri Oginni will deliver the keynote address, focusing on the insurance perspective while Mr. Oguche Aguda, Founder and Managing Partner of HRISP Partners will equally deliver a paper on the theme, focusing on the pension perspective.

The Group Managing Director of Custodian Investment Plc, Mr. Wole Oshin will chair the event.

According to NAIPE, the conference is coming at a critical period for the two sectors, as insurance operators have just concluded their recapitalisation exercise while pension operators are expected to conclude theirs in 2027.

The high-level discourse will therefore examine how funds raised through recapitalisation can be strategically invested and deployed to generate stronger returns, deepen market confidence and improve service delivery to shareholders and policyholders.

Expected dignitaries include the Commissioner for Insurance & Chief Executive Officer of the National Insurance Commission (NAICOM), Mr. Olusegun Omosehin; Director-General of the National Pension Commission (PenCom), Ms. Omolola Oloworaran; chief executives of insurance companies, broking firms, investment and securities companies and Pension Fund Administrators (PFAs), as well as regulators, labour unions, students and other stakeholders.

Speaking ahead of the conference, Chairperson of NAIPE, Mrs. Ebere Nwoji said the annual gathering provides a platform for insurance and pension journalists to contribute to the development of both sectors by promoting greater public understanding of insurance and pension as instruments for financial security and protection against old-age poverty.

Nwoji expressed appreciation to operators and regulators in the two sectors for their continued support for the conference, stressing that the benefits derived from the annual event outweighs the resources committed in organising it.

She described this year’s theme as timely, given the significant structural changes taking place in the insurance and pension industries through recapitalisation.

The NAIPE chairperson, particularly commended the leadership of NAICOM for successfully concluding the insurance industry’s recapitalisation exercise, describing it as a major achievement for the Commission.

She also expressed optimism that the pension industry under the leadership of Ms. Omolola Oloworaran, would achieve a seamless and successful recapitalisation exercise.

“The conference would provide operators with an opportunity to gain insights into prudent and judicious investment of the capital raised through the recapitalisation process.

“I am confident that speakers at the event would provide practical perspectives on how insurance and pension operators can deploy their strengthened capital bases to deliver superior investment returns while enhancing value for investors, shareholders and policyholders” she affirmed.

Meanwhile, NAICOM, PenCom, SanlamAllianz, Veritas Kapital and 24 others have offered their support and partnership towards the hosting of the conference.

Debit Card vs Credit Card: How to Choose the Right Card for Every Expense

0

Understanding what happens to your money after a payment is just as important as completing the transaction.

Picture a professional preparing for a trip. The flight must be booked, the hotel needs to be paid for and regular household expenses have not stopped simply because travel is approaching.

There are two cards in the wallet, a debit card and a credit card.

Both cards can be used to make payments, but they affect the cardholder’s finances differently. A debit card draws money directly from the available balance in a linked bank account. A credit card allows the cardholder to borrow within an approved credit limit and repay the amount under agreed terms.

Understanding the difference between a debit card and a credit card is the first step towards choosing the right payment option for every expense.

What is the difference between a debit card and a credit card?

The main difference lies in the source of the money used for a transaction.

When you pay with a debit card, you are spending money already available in your bank account. When you use a credit card, you are accessing an approved borrowing facility that must be repaid.

This distinction affects budgeting, repayment obligations and the overall cost of a purchase. Before selecting either card, consider whether you want to pay immediately from your available funds or repay the amount later under the applicable credit terms.

When should you use a debit card?

A debit card may be suitable for everyday expenses such as groceries, fuel, utility payments, subscriptions and meals.

Because each payment is deducted from the linked account, a debit card creates a direct relationship between spending and the available account balance. This can help customers who prefer to keep routine expenses closely aligned with money they already have.

Fidelity Bank offers debit card options for different payment needs, including Naira and Dollar cards. Customers should select a card based on where they intend to use it, the transaction currency and the applicable terms.

Before making a payment, it is important to confirm that the account has sufficient funds and that the card supports the intended transaction.

When should you consider a credit card?

A credit card can provide financial flexibility when the timing of an expense does not match the timing of available funds.

For example, a traveller may need to pay for a flight or hotel before receiving an expected payment. A credit card can help bridge that timing gap, provided there is a clear and realistic repayment plan. 

Before using a credit card, ask three important questions:

  • Is the purchase necessary?
  • Can I repay the amount by the due date?
  • What will happen if the expected funds arrive late?

An available credit limit shows how much the cardholder is permitted to borrow. It does not automatically determine how much the customer can comfortably afford to spend.

How to use a credit card responsibly

Credit-card flexibility works best when it is supported by proper planning.

Before completing a transaction, review the applicable interest rate, fees, repayment date and minimum payment requirement. Paying only the minimum amount may leave an outstanding balance that continues to attract interest in line with the card’s terms.

A responsible credit-card plan should identify the source of repayment, the expected repayment date and the total potential cost of the transaction.

These considerations apply to major expenses and smaller purchases. Several modest transactions can accumulate into a significant outstanding balance if spending is not monitored carefully.

Choosing a card for international travel

When choosing a card for travel, customers should look beyond the payment itself. Currency, card acceptance, travel frequency, repayment capacity and available benefits may all influence the decision.

A debit card allows the traveller to spend from available funds, while a credit card provides access to an approved credit facility. The better option will depend on the traveller’s financial habits, destination and ability to manage repayment.

For customers considering premium cards, the value of travel-related benefits should also be assessed against how frequently those benefits will be used.

Fidelity Bank Visa Signature and Visa Infinite Cards

Fidelity Bank’s premium card offering includes the Visa Signature Debit Card and Visa Infinite Credit Card.

The Visa Signature Debit Card draws from the customer’s available funds, while the Visa Infinite Credit Card provides an approved credit facility.

Benefits associated with the Visa Infinite Credit Card include unlimited complimentary access to more than 850 LoungeKey lounges for the cardholder and one guest per visit, concierge services, benefits at more than 900 hotels, multi-trip travel insurance and discounted personal fast-track services at more than 380 international airports.

For frequent travelers, airport lounge access can provide a more comfortable place to wait between flights, while concierge services may assist with selected travel arrangements. The value of these benefits will depend on usage, eligibility and the applicable terms.

Customers considering the Visa Signature Debit Card should also review its separate benefits schedule before making a decision.

Debit card or credit card: Which is better?

Neither option is automatically better for every customer or transaction. The right card is the one that fits the customer’s spending habits, financial position and repayment capacity.

A practical approach may be to use:

A debit card for routine expenses and purchases that can be paid for immediately.

A credit card selectively for planned expenses supported by a clear repayment strategy.

A premium debit or credit card when the associated travel and lifestyle benefits match established spending patterns.

The objective is to choose deliberately rather than simply using whichever card is closest at the time of payment.

How to request a Fidelity Bank card

Eligible Fidelity Bank debit cards can be requested through the Fidelity Mobile App. Customers interested in a credit card or Fidelity Bank’s premium card suite can visit a branch or speak with a relationship manager to discuss eligibility, fees, repayment terms and available benefits.

Before applying, customers should review the card’s currency, charges, transaction limits, repayment obligations and benefit terms.

Make every card payment a considered decision

Choosing between a debit card and a credit card begins before the transaction.

Ask yourself whose money is being spent today, how the payment will affect your available balance and what financial obligation will remain tomorrow.

When the card matches the expense and the customer has a clear spending or repayment plan, it becomes more than a convenient payment tool. It becomes part of responsible money management