Home Blog Page 4

FSI, NCC Empower Female Students in Northern Nigeria with Digital Skills, 15 Selected for Industry Internships

0


  • Eight-week Fundamentals of Software Testing programme attracts 590 applications, records 95 graded participants and creates a pathway to industry experience through a five-week internship with GoAssurify Limited

Financial Services Innovators (FSI), with sponsorship from the Nigerian Communications Commission (NCC), has successfully concluded its eight-week Fundamentals of Software Testing Training Programme for Female University Students in Northern Nigeria, equipping young women with practical digital skills and creating pathways to industry experience for outstanding participants.

The programme ran from 8 August to 26 September 2026 and reached female students across Kano, Nasarawa, Bauchi, Sokoto and Katsina States. It attracted 590 applications, reflecting significant interest in technology skills development among young women in the region.

After the selection process, 115 female students were admitted; 95 participated, submitted programme deliverables, and received final grades.

A major outcome of the programme was the selection of 15 outstanding participants for a five-week internship with GoAssurify Limited starting in November 2026. The internship will provide an opportunity for the awardees to build on their training and gain further exposure to professional software testing practices.

From Training to Industry Experience

The programme was designed to equip female tertiary institution students with foundational and practical software testing competencies relevant to the technology industry.

Over eight weeks, participants received training in software testing principles, software development life cycle models, test case design, defect management, web application testing and API testing. The curriculum incorporated practical assignments and collaborative projects involving web and API testing simulations, with exposure to industry tools such as Jira and Postman.

The initial six-week curriculum was extended by two weeks to allow additional time for hands-on assignments and provide support to students experiencing connectivity challenges and other learning barriers.

Participants were assessed using a 200-point grading framework covering practical projects, assignments, participation, group work and attendance. The assessment process identified 15 internship awardees and six students who achieved scores of 70% and above.

The transition to a five-week internship with GoAssurify Ltd. represents an important step in connecting technical training with professional exposure, helping participants deepen their understanding of how software testing skills are applied in the workplace.

Meet the 15 Internship Awardees

Following the programme’s assessment process, the following 15 participants were selected for the five-week internship with GoAssurify Limited commencing in November 2026:

  • Khadija Umar Danhassan
  • Comfort Ali Adamu
  • Hauwa Muhammed Alhassan
  • Laila Usman
  • Hamidat Olaoti
  • Badmus Oluwatosin
  • Maryam Bulama Laminu
  • Aminu Sahiba Agbo
  • Isma’il Fadila Adam
  • Rasheedat Abdulazeez
  • Maryam Balarabe Adamu
  • Ada Blessing Emmanuel
  • Bilkisu Muhammad Ahmad
  • Abdullahi Aisha Adamu
  • Maryjane Adebayo

FSI congratulates all 15 awardees on their achievement and commends their commitment to developing their technical capabilities. Their selection underscores the importance of identifying promising talent and providing young women with opportunities to progress from structured training to practical industry experience.

Khadija Umar Danhassan Emerges as Overall Best Performer

Special recognition goes to Khadija Umar Danhassan, a Computer Science student at the National Open University of Nigeria who resides in Kano State, who emerged as the programme’s overall best performer with an impressive score of 93.5%.

Her achievement highlights the potential of young women to excel in technology when they have access to relevant training, practical learning opportunities and support to develop industry-ready skills.

Khadija’s performance is a notable example of the talent that targeted digital skills programmes can identify and nurture among female students in Northern Nigeria.

FSI Executive Director: Closing the Gender Gap Requires Skills, Mentorship and Opportunity

Commenting on the successful completion of the programme, Dr Aituaz Kola-Oladejo, Executive Director of Financial Services Innovators (FSI), said:

“At FSI, we believe that bridging the gender gap in technology requires more than encouraging young women to consider careers in tech. It requires giving them access to relevant skills, practical learning opportunities, industry mentors and clear pathways into the workplace.

“The response to this programme, with 590 applications from across Northern Nigeria, demonstrates the interest among young women in participating in the digital economy. We are particularly encouraged that 95 students completed the programme requirements and that 15 outstanding participants will progress to a five-week internship with GoAssurify Ltd. in November.

“With the support of the Nigerian Communications Commission, we are helping to turn that interest into practical capability and opportunity. Through our SmartGirls Initiative Africa, we want more young women to see themselves not just as users of technology, but as the professionals who test, develop, secure and build the digital solutions shaping our future.

“Our ambition is to expand these opportunities across Nigeria and Africa, ensuring that more young women can access the skills, mentorship and industry connections needed to participate meaningfully in the digital economy.”

SmartGirls Initiative Africa: Four Technology Tracks for Young Women

The Fundamentals of Software Testing programme is part of FSI’s SmartGirls Initiative Africa, designed to bridge the gender gap in technology in Nigeria and across Africa by honing young women’s skills and connecting them with industry professionals.

SmartGirls is structured around four technology tracks:

  • Artificial Intelligence (AI): Introducing young women to emerging AI technologies and their practical applications.
  • Software Testing: Building competencies in software quality assurance, test design, defect identification and testing practices.
  • Software Development: Developing the technical foundations needed to design, build and improve digital products and applications.
  • Cybersecurity: Developing skills and awareness relevant to protecting digital systems, applications and information.

Beyond technical training, the initiative aims to connect students with industry mentors who can offer insight into workplace expectations, professional standards, career pathways and the practical competencies needed to succeed in technology roles.

By combining technical skills development with mentorship and opportunities for practical experience, SmartGirls aims to help young women make informed career decisions and prepare for the realities of working in the technology sector.

Making Technology More Accessible Across Academic Disciplines

The programme demonstrated that technology skills are relevant to students from diverse academic backgrounds. In addition to students studying computer science, software engineering, information technology and related disciplines, participants came from fields including nursing, the biological and chemical sciences, mass communication, accounting, business administration, engineering, law and education.

This diversity reinforces the message that women from different educational backgrounds can begin developing valuable technology competencies and explore opportunities in the digital economy.

Female peer volunteers also contributed to the programme by supporting their colleagues, fostering collaboration, and helping sustain engagement throughout the training. Their contributions highlighted the value of peer learning and community support in strengthening women’s participation in technology.

The programme also identified challenges, including unreliable internet connectivity, power supply interruptions and limited access to suitable devices. These lessons will inform future efforts to improve accessibility and expand participation in subsequent cohorts.

Building a Stronger Pipeline of Female Technology Talent

The successful conclusion of the programme represents a measurable step towards expanding the pipeline of female technology talent in Northern Nigeria.

Through the NCC-sponsored initiative, FSI has helped identify promising young women, assess their practical capabilities and create a pathway to further professional development through the forthcoming internship phase.

FSI will continue advancing the SmartGirls Initiative Africa, working to broaden access to industry-relevant skills, professional mentorship, and practical learning opportunities across its four technology tracks.

FSI appreciates the Nigerian Communications Commission for sponsoring the programme, GoAssurify Limited for hosting the internship, the participating tertiary institutions, programme facilitators and peer volunteers, and all the students who committed to learning and developing their skills. 

About Financial Services Innovators (FSI)

Financial Services Innovators (FSI) is committed to strengthening innovation, developing digital capabilities and expanding opportunities for participation across the technology and financial services ecosystem. Through its initiatives, FSI supports skills development, employability and inclusion, helping young people build the capabilities and industry connections needed to participate in the digital economy.

About SmartGirls Initiative Africa

SmartGirls Initiative Africa is an FSI initiative focused on bridging the gender gap in technology by equipping young women with relevant skills across Artificial Intelligence, Software Testing, Software Development and Cybersecurity.

The initiative also aims to connect participants with industry mentors and practical learning opportunities to deepen their understanding of professional expectations and prepare them for careers in technology.
NAICOM Chief, Segun Omosehin, Senator Abiru Inducted as Fellows of NCRIB

0

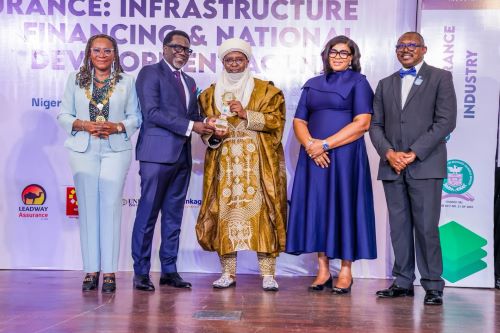
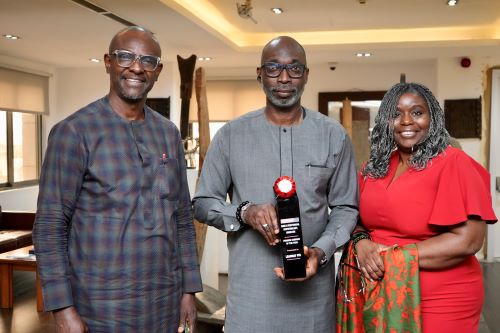
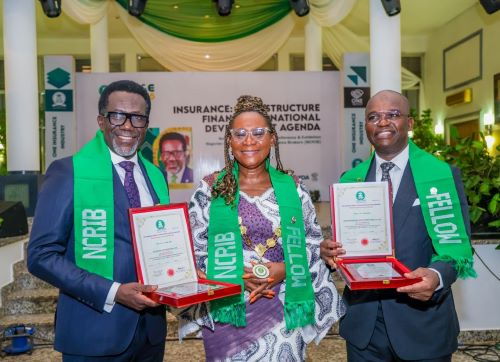
L–R: Mr. Olusegun Ayo Omosehin, Commissioner for Insurance; Mrs. Ekeoma Ezeibe, FCIB, President of the Nigerian Council of Registered Insurance Brokers (NCRIB) and Senator Adetokunbo Abiru, Chairman of the Senate Committee on Banking, Insurance and Other Financial Institutions.

The Commissioner for Insurance and Chief Executive Officer of the National Insurance Commission (NAICOM), Mr. Olusegun Ayo Omosehin, has been inducted as a Fellow of the Nigerian Council of Registered Insurance Brokers (NCRIB) alongside Senator Adetokunbo Abiru, Chairman of the Senate Committee on Banking, Insurance and Other Financial Institutions.

The conferment took place during a gala dinner hosted by the NCRIB in Abuja on Wednesday, bringing together prominent stakeholders from Nigeria’s insurance, banking, and wider financial services sectors.

The fellowship, one of the highest honours bestowed by the Council, recognises individuals who have made significant contributions to the growth, development, and advancement of the insurance industry and the financial services sector in Nigeria.

Speaking at the event, NCRIB President commended the inductees for their outstanding leadership, professionalism, and commitment to strengthening the nation’s financial ecosystem.

The ceremony provided a platform for industry leaders, regulators, policymakers, and practitioners to engage on key issues affecting the insurance sector and to reinforce collaboration towards enhancing insurance penetration and financial inclusion across the country.

Mr. Omosehin’s induction further underscores his contributions to the transformation and regulation of Nigeria’s insurance industry, while Senator Abiru was recognised for his support in advancing legislative initiatives that promote the growth and stability of the financial services sector.

Polaris Bank Deepens Sustainability Commitment with Tree Planting at Lekki Conservation Centre

0

L-R: Mr. Uchenna Achunine, Director Business Dev & Partnership at the Nigerian Conservation Foundation (NCF); Pius Olaoye, CFO, Polaris Bank; Abimbola Ozomah, Executive Director, Corporate & Investment Banking, Polaris Bank; Dr. Joseph Onoja, DG NCF; Bukola Oluyadi, Group Head Customer Experience & Value Management, Polaris Bank and Rasheed Bolarinwa, Head, Brand Management & Corporate Communications, Polaris Bank at the Tree Planting Exercise.

Polaris Bank has reinforced its commitment to environmental sustainability with a tree-planting exercise at the Lekki Conservation Centre, Lagos, in collaboration with the Nigerian Conservation Foundation (NCF), as part of its ongoing efforts to promote climate action, environmental conservation and sustainable community development.

The exercise, held on Monday, builds on the Bank’s nationwide tree-planting initiative launched in 2024. Since its inception, the initiative has recorded the planting of 10,000 trees across 16 locations in the Federal Capital Territory (FCT) and 13 states across Nigeria, reflecting the Bank’s commitment to translating its sustainability principles into measurable impact.

Speaking at the event, Abimbola Ozomah, Executive Director, Corporate & Investment Banking, Polaris Bank, reaffirmed the Bank’s commitment to embedding sustainability into its operations and community engagement efforts.

“At Polaris Bank, sustainability is not a slogan, it is a principle that guides our daily actions. It is about transforming bold commitments into measurable impact. Each of these trees represents more than just a number; they stand for communities empowered, degraded lands restored, and livelihoods supported,” she said.

She noted that the partnership with the Nigerian Conservation Foundation at the Lekki Conservation Centre represents another important step in the Bank’s sustainability journey. According to her, planting economic trees goes beyond addressing climate change, as it also creates opportunities for long-term community benefits, including improved soil fertility, increased vegetation cover and potential income generation as the trees mature.

Ozomah further emphasised that building a sustainable future requires collective responsibility, noting that staff, partners and other stakeholders all have important roles to play in advancing environmental conservation.

“The power of small actions, when multiplied, creates extraordinary change. As we put these seedlings into the ground, let us commit to nurturing them and, in so doing, nurturing the future we all desire. Together, let us grow a greener, stronger, and more sustainable Nigeria,” she added.

The tree-planting exercise underscores Polaris Bank’s continued support for practical environmental initiatives that contribute to climate resilience, ecological restoration and community development.

Through its nationwide tree-planting programme and partnerships with organisations such as the NCF, the Bank continues to encourage collective action towards protecting the environment and building a more sustainable future for generations to come.


NAICOM: Brokers Remain Key Stakeholders in Insurance Growth, Penetration in Nigeria

0

L–R: Mrs. Ekeoma Ezeibe, FCIB, President of the Nigerian Council of Registered Insurance Brokers (NCRIB); Mr. Olusegun Ayo Omosehin, Commissioner for Insurance; Alhaji Mohammed Kari, Waziri of Bauchi and former Commissioner for Insurance; Mrs. Ebelechukwu Nwachukwu, Chairman of the Nigerian Insurers Association (NIA) and Mr. Akinjide Orimolade, President of the Chartered Insurance Institute of Nigeria (CIIN).

OPENING ADDRESS BY THE COMMISSIONER FOR INSURANCE / CHIEF EXECUTIVE OFFICER OF THE NATIONAL INSURANCE COMMISSION (NAICOM), MR. OLUSEGUN AYO OMOSEHIN, AT THE OCCASION OF THE 2026 NATIONAL INSURANCE BROKERS CONFERENCE AND EXHIBITION HELD AT SHEHU MUSA YAR’ADUA CENTER, ABUJA ON WEDNESDAY, 21 OCTOBER 2026 BY 9.OO AM

Theme: Insurance: Infrastructure Financing & National Development Agenda

It gives me great pleasure to join you today at the 2026 National Insurance Brokers Conference and Exhibition.

On behalf of the Management and Staff of the National Insurance Commission (NAICOM), I commend the Governing Board and entire membership of the Nigerian Council of Registered Insurance Brokers (NCRIB) for convening this vital national dialogue.

The theme chosen for this year’s conference “Insurance: Infrastructure Financing & National Development Agenda” could not be more apt or timely. As Nigeria advances toward sustainable economic renewal and a multi-trillion-dollar economy, the imperative for long-term domestic capital formation and robust risk management mechanisms has never been clearer. 

THE ROLE AND CONTRIBUTION OF INSURANCE BROKERS

Insurance brokers occupy a central and indispensable position within the Nigerian insurance ecosystem. As trusted risk advisors, intermediaries, and advocates for policyholders, brokers generate a significant portion of the total premium volume in our market.

Your contribution extends far beyond commercial transactions:

* Market Expansion & Penetration: Brokers serve as the primary bridge connecting policyholders to underwriting institutions, simplifying complex risks, and building public trust across corporate, public, and retail sectors.

* Risk Structuring for Capital Projects: As the nation undertakes mega-infrastructure projects in transport, energy, real estate, and industrialization, insurance brokers provide the technical expertise required to structure complex risk mitigation and risk transfer solutions.

* Professionalism & Consumer Protection: Through advisory services, risk auditing, and prompt claims negotiation, brokers ensure policyholders enjoy maximum value and protection.

NAVIGATING THE NIGERIAN INSURANCE INDUSTRY REFORM ACT (NIIRA)

This conference takes place at a historic junction in our regulatory history following the enactment of the Nigerian Insurance Industry Reform Act (NIIRA).

NIIRA represents a total modernization of our legal and regulatory framework, designed to strengthen balance sheets, enforce sound market conduct, protect consumers, and accelerate insurance penetration.

For Insurance Brokers, this landmark legislation presents both a higher standard of accountability and unprecedented growth opportunities:

* Enhanced Professional Standards & Strict Governance: NIIRA introduces stricter market conduct requirements and elevated licensing regimes. Unlicensed activities, ethical lapses, and non-remittance of premiums carry far-reaching consequences. The Commission will strictly enforce these rules to protect consumer confidence.

* Digital Transformation & Innovation: The Act formally recognizes digital, electronic, and web-based insurance channels. Brokers are urged to leverage technology and InsurTech solutions to expand their market reach and streamline customer experiences.

* Unlocking Infrastructure Financing: NIIRA expands and enforces compulsory insurance classes while providing stronger frameworks for institutional investment. Brokers must position themselves as capital catalysts guiding infrastructure sponsors, contractors, and financiers on the compulsory and customized risks required for major national assets.

I encourage all delegates at this conference to actively deliberate on how the provisions of NIIRA can guide brokerage firms to build stronger governance structures, foster ethical market conduct, and scale up operations. 

 ALIGNING WITH THE NATIONAL INFRASTRUCTURE & DEVELOPMENT AGENDA

Infrastructural deficits cannot be bridged without sustainable risk management and local capital participation. Through pool funds, infrastructure bonds, and tailored risk guarantees, the insurance sector must step up as a key enabler of national development.

NAICOM remains fully committed to creating an enabling environment that encourages product innovation, capital growth, and market expansion. We expect NCRIB and its members to lead from the front by building strategic alliances across the banking, energy, manufacturing, and public infrastructure sectors. 

CONCLUSION

I applaud the NCRIB leadership once again for organizing this impactful conference. NAICOM will continue to support the Council in upgrading professional skills, enforcing market discipline, and advancing the national growth agenda.

I urge us all to view this conference as an opportunity to move beyond discussions and develop practical recommendations that will strengthen the brokerage profession, advance the implementation of NIIRA 2025 and position insurance as a more effective instrument for infrastructure financing and national development.

Let us work together to build an industry that commands public trust, delivers value to policyholders and contributes meaningfully to Nigeria’s economic aspirations.

It is now my singular honor and privilege to formally declare open the 2026 National Insurance Brokers Conference and Exhibition.

I wish you fruitful, enriching, and impactful deliberations.

Thank you, and God bless the Federal Republic of Nigeria

PRESIDENCY RESPONDS TO GOVERNOR MAKINDE’S CLAIM ON NLNG DIVIDENDS

0

The Presidency wishes to clarify Governor Seyi Makinde’s claim that the Federal Government is withholding ₦250 billion in NLNG dividends for each state of the Federation.

At the 2027 Budget Stakeholders’ Consultative Engagement held at the Olola Ogunlana Hall, International Conference Centre, University of Ibadan, on Friday, Makinde claimed the funds would not be released until after the 2027 elections. He further claimed that the Federal Government had spent the money.

“Each state was supposed to get ₦250 billion. We had already identified projects that would expand Oyo State’s economy. But they have now said the money will not be paid until after the election. Is the election more important than the people of Nigeria?” the governor said.

Makinde’s latest claim that the Federal Government is withholding the NLNG dividend windfall is false and should be disregarded.

Here are the facts the public should know about how the Federation Account is managed and how money is shared among the three tiers of government. Even as a one-off distribution, ₦250 billion to each of the 36 states amounts to ₦9.0 trillion, excluding the Federal Government, the FCT, and the 774 local councils.

Under the Federation Account Allocation Committee (FAAC) formula, states receive 26.72% of the distributable Federation Account revenue. For the states’ share alone to reach ₦9 trillion, total NLNG dividends paid into the Federation Account would have to exceed ₦33.68 trillion (about $25 billion) in a single declaration.

NLNG has never paid $25 billion in dividends to the Federation Account in a single payout.

NLNG and Historical Dividend Context:

NLNG has paid approximately $21.5 billion in dividends to the Federation over the last 25 years, with less than $3 billion realised since President Bola Ahmed Tinubu assumed office.

Therefore, any claim that a single payout exceeds the company’s entire lifetime distribution to the Federation—and is being withheld—defies basic logic and economic reality.

We expect Governor Makinde to be more measured in his public conduct and utterances. Since he embarked on his presidential bid, he has chosen to play politics by making misleading claims rather than presenting verifiable facts. Indeed, he has turned false, unguarded statements and claims into an art form.

He once described the huge financial flow from the federation account to states, including Oyo, as ‘voodoo’.

Under Nigerian law, Governor Makinde is free to pursue his presidential ambition. He should desist from making falsehoods and disinformation the hallmarks of his campaign.

We urge the public to disregard these unfounded claims, which serve only to mislead citizens and stoke needless disaffection against the Federal authorities. 

Bayo Onanuga

Special Adviser to the President

(Information and Strategy)

October 18, 2026

FG: Interest Payment on Loans 60% of Revenue not 124%: Setting the Record Straight

0

The Federal Ministry of Finance has noted recent analysis and public commentary which, citing the World Bank’s October 2026 Nigeria Development Update, claims that Federal Government interest payments reached 124% of revenue in the first half of 2026. This conclusion is misleading, for three reasons.

  1. 𝐈𝐭 𝐜𝐨𝐦𝐩𝐚𝐫𝐞𝐬 𝐦𝐢𝐬𝐦𝐚𝐭𝐜𝐡𝐞𝐝 𝐟𝐢𝐠𝐮𝐫𝐞𝐬 𝐚𝐠𝐚𝐢𝐧𝐬𝐭 𝐚𝐧 𝐢𝐧𝐜𝐨𝐦𝐩𝐥𝐞𝐭𝐞 𝐫𝐞𝐯𝐞𝐧𝐮𝐞 𝐛𝐚𝐬𝐞.

The interest figure includes debt the Federal Government services on behalf of other tiers of government, including external loans to states. Measuring this against federal revenue alone overstates the ratio which is only meaningful when debt and revenue cover the same level of government.

The reported revenue is also incomplete. It excludes independent revenue already earned by government agencies and enterprises but not yet remitted to the Treasury.

In addition, more revenue is typically earned in the second half of the year than in the first due to the statutory timing of certain tax payments. This is why the ratio stood at 156% in H1 2025, while the full-year 2025 debt-service-to-revenue ratio was below 60%, down from 97% before the reforms. This is a clear sign of the progress delivered by the current administration’s reforms. 

  1. 𝐄𝐯𝐞𝐧 𝐨𝐧 𝐭𝐡𝐞 𝐬𝐚𝐦𝐞 𝐜𝐚𝐥𝐜𝐮𝐥𝐚𝐭𝐢𝐨𝐧, 𝐭𝐡𝐞 𝐩𝐨𝐬𝐢𝐭𝐢𝐨𝐧 𝐡𝐚𝐬 𝐢𝐦𝐩𝐫𝐨𝐯𝐞𝐝 𝐬𝐢𝐠𝐧𝐢𝐟𝐢𝐜𝐚𝐧𝐭𝐥𝐲.

Between the first half of 2025 and the first half of 2026, federal revenue rose by 72%, from ₦3.6 trillion to ₦6.2 trillion. Interest payments rose by a much slower 38%, from ₦5.6 trillion to ₦7.7 trillion. Revenue is therefore growing almost twice as fast as interest costs.

As a result, the interest-to-revenue ratio fell by 32 percentage points in a single year, from 156% to 124%, and the gap between interest and revenue narrowed from ₦2.0 trillion to ₦1.5 trillion. This is the result of reforms working, not a sign of fiscal distress. 

  1. 𝐀 𝐡𝐚𝐥𝐟–𝐲𝐞𝐚𝐫 𝐬𝐧𝐚𝐩𝐬𝐡𝐨𝐭 𝐢𝐬 𝐧𝐨𝐭 𝐚 𝐦𝐞𝐚𝐬𝐮𝐫𝐞 𝐨𝐟 𝐝𝐞𝐛𝐭 𝐬𝐮𝐬𝐭𝐚𝐢𝐧𝐚𝐛𝐢𝐥𝐢𝐭𝐲.

Debt sustainability is assessed on a full-year basis, not over six months. The same World Bank report projects Nigeria’s full-year 2026 debt service, covering both interest and principal, at 46% of revenue. This is the appropriate benchmark, and a guide to avoid the invalid conclusions being drawn.

𝐀𝐥𝐥 𝐛𝐨𝐫𝐫𝐨𝐰𝐢𝐧𝐠 𝐢𝐬 𝐥𝐚𝐰𝐟𝐮𝐥 𝐚𝐧𝐝 𝐚𝐩𝐩𝐫𝐨𝐯𝐞𝐝.

Every naira borrowed by the Federal Government falls within the limits approved by the National Assembly under the 2026 Appropriation Act and the approved borrowing plan. All borrowing is conducted in full compliance with the Fiscal Responsibility Act 2007 and the Debt Management Office (Establishment) Act 2003, and is published regularly by the Debt Management Office.

The Ministry welcomes informed scrutiny of public finances. We encourage analysts and commentators to apply the same rigour they seek to hold the government to: compare like with like, read figures in context, and seek clarification where the data is unclear. 

𝐒𝐢𝐠𝐧𝐞𝐝:

𝘍𝘦𝘥𝘦𝘳𝘢𝘭 𝘔𝘪𝘯𝘪𝘴𝘵𝘳𝘺 𝘰𝘧 𝘍𝘪𝘯𝘢𝘯𝘤𝘦

𝘏𝘦𝘢𝘥𝘲𝘶𝘢𝘳𝘵𝘦𝘳s

Abuja, 18 October 2026

RMB Nigeria Asset Management Wins Excellence in Investment Management at 2026 BAFI Awards

0

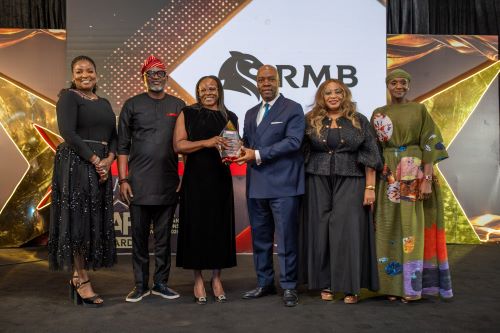
L-R: Yetunde Ogunremi, Non-Executive Director, RMB Nigeria Asset Management Limited; ‘Shola Ogunyemi, Head, Marketing & Communications, RMB Nigeria; Kike Mesubi, CEO RMB Nigeria Asset Management Limited; Patrick Akinwuntan, immediate past CEO, Ecobank Nigeria; Kikelomo Olukoya, Head, Business Development, RMB Nigeria Asset Management; Nadia Zakari, Non-Executive Director, RMB Nigeria Asset Management Limited during the presentation of the award of Excellence in Investment Management at the 2026 Banks and Other Financial Institutions (BAFI) Awards.

RMB Nigeria Asset Management Limited has been honoured with the Excellence in Investment Management award at the 2026 Banks and Other Financial Institutions (BAFI) Awards, celebrating the firm’s exceptional performance and dedication to delivering superior investment solutions.

This prestigious category win recognises RMB Nigeria Asset Management’s rigorous investment expertise, disciplined risk management, and steadfast commitment to generating sustainable, long-term value for its clients.

Commenting on the recognition, Kike Mesubi, Chief Executive Officer of RMB Nigeria Asset Management Limited, said:

“This recognition reflects our commitment to disciplined investment management, informed decision-making and a clear understanding of our clients’ objectives. In a market shaped by changing economic conditions, our focus remains on applying rigorous analysis and sound risk management to deliver investment solutions aligned with our clients’ needs and long-term goals. We are proud of this recognition and remain committed to creating lasting value for the clients that place their trust in us.”

Operating in a dynamic financial landscape, the firm offers a diverse suite of tailored investment solutions spanning money market, fixed income, bespoke solutions, access to offshore investments and alternative investment solutions. These solutions are designed to align with the return and risk objectives and financial objectives of individual, corporate and institutional investors.

This recognition reflects the firm’s focus on combining macroeconomic insight, investment expertise and a client-centric approach to navigating evolving market conditions and changing investor behaviour.

ABOUT RMB NIGERIA ASSET MANAGEMENT LIMITED

RMB Nigeria Asset Management Limited (RMBN AM), a wholly owned subsidiary of FirstRand Limited, one of Africa’s leading financial services groups headquartered in South Africa, is the group’s dedicated wealth and asset manager in Nigeria.

Registered and regulated by the Securities and Exchange Commission, Nigeria. RMBN AM combines deep local market expertise with global best practice to deliver investment solutions that help clients grow, preserve and manage wealth with confidence.

.

Nigeria Ranks 3rd in Mobile Web Browsing Performance among Top 5 Nations

0
 

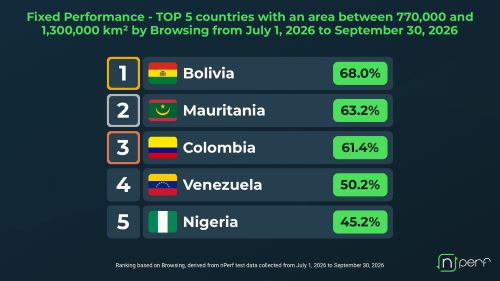
According to nPerf data, Nigeria ranks 3rd in mobile web browsing performance between July and September 2026, among the top 5 countries with a land area between 770,000 and 1,300,000 km². With a score of 39.32%, it delivers a web page loading experience close to that of Egypt (39.66%).

·         Nigeria among the leaders in web browsing performance

Nigeria achieves a score of 39.32% in mobile web browsing performance, ranking just behind Egypt (39.66%). This result reflects smooth access to the country’s most visited websites, essential for an optimal user experience.

·         Significant performance gaps between countries

Performance varies significantly: Venezuela scores 34.17%, while South Africa reaches 33.15%. These differences highlight disparities in mobile connection quality for web browsing within this group of countries.


About nPerf

nPerf is an independent platform for measuring Internet performance, based on real user experience.

By converting millions of connection tests into actionable insights, nPerf helps operators improve their networks and contributes to building a faster, more reliable Internet for everyone.

Leadway PFA Emerges Pension Company of the Year at BAFI Awards

0

(L-R) Executive Director, Sales, Leadway PFA, Oluwafemi Adebayo; Managing Director/Chief Executive Officer, Leadway PFA, Olusakin Labeodan; Executive Director, Investment, Leadway PFA, Yemisi Rotimi, during the presentation of the BusinessDay BAFI Award for Pension Company of the Year to Leadway PFA’s management at the company’s corporate office in Lagos on October 13, 2026.

Leadway PFA, one of Nigeria’s pension fund administrators with significant asset under management, has been named Pension Company of the Year at the 14th BusinessDay Banks and Other Financial Institutions (BAFI) Awards 2026, recognising its stellar performance in redefining pension security and long-term wealth creation in Nigeria.

The PFA of the Year award recognises pension administrators that demonstrate strong performance across investment management, contributor growth, customer experience, technological capability and retirement access to workforce.

For Leadway PFA, the recognition builds on more than 20 years of experience in pension administration and fund management. Following the successful integration of Leadway Pensure and PAL Pensions, and rebranding as Leadway PFA, the company now manages over ₦3 trillion in assets for more than 1.2 million Retirement Savings Account holders, strengthening its capacity to serve contributors through its investment expertise and continued efforts to make pension services more accessible.

Commenting on the award, Olusakin Labeodan, Managing Director and Chief Executive Officer of Leadway PFA, said: “Being named PFA of the Year at the 2026 BusinessDay BAFI Awards is an exemplary recognition for Leadway PFA’s expertise, governance and innovations that we bring to pension administration. It reflects our work in investment management, customer service, and developing pension solutions that meet Nigerians’ evolving needs.”

“Over the past two decades, we have built our capabilities around helping individuals prepare for retirement, and we are grateful to our contributors for the trust they place in us. We are proud of what our team has achieved and see this award as an opportunity to build on that record, raise our standards further and deliver greater value to our contributors throughout their retirement journey.”

The company continues to build on its customer service capabilities and digital pension solutions to make retirement planning and pension management more accessible to Nigerians. With its growing contributor base and assets under management, Leadway PFA remains focused on helping individuals and organisations prepare for retirement through effective pension administration and long-term fund management.

Leadway PFA has also earned recognition for its customer service. In 2025, the company received a Gold Award for Customer Service Excellence at the West Africa Innovation Awards for the third consecutive year. It was also named West Africa Pension & Lifestyle Company of the Year, following similar wins in 2023 and 2024. These accolades add to the recognition the company has received for its service delivery and contribution to the pension industry.

Organised by BusinessDay Media Limited, the BAFI Awards recognises excellence across Nigeria’s financial services industry. Now in its 14th edition, the awards spotlight institutions whose performance, leadership and innovation contribute to the development of their respective sector.

Stanbic IBTC Champions Collaboration to Transform Nigerian Research into Commercial Opportunities

0

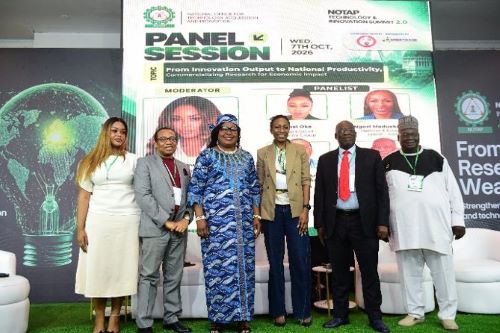
L–R: Hillary Nwogwu, Chief Executive Officer, Hilora Staffing Solution; Ndukwe Anagha, Head, Information Technology Department, Stanbic IBTC Pension Managers; Dr. (Barr.) Lady Obiageli Edith Amadiobi, Director-General/Chief Executive Officer, National Office for Technology Acquisition and Promotion (NOTAP); Ngozi Madueke-Dozie, Platform and Ecosystem Leader, Google; Prof. Peter Bamkole, Deputy Vice-Chancellor, Pan-Atlantic University; and Mr. Anpe F. Michael, Director, Technology Acquisition and Adaptation, representing Dr. Mukhtar Yawale Muhammned, Permanent Secretary, Federal Ministry of Innovation, Science and Technology, during the NOTAP Technology and Innovation Summit 2.0, co-sponsored by Stanbic IBTC, held recently in Lagos.

Stanbic IBTC, a member of Standard Bank Group, has reaffirmed the importance of collaboration, relevant skills and access to finance in transforming Nigerian research and innovation into commercially viable enterprises.

The Group reinforced this position through its sponsorship of and participation in the second edition of the National Office for Technology Acquisition and Promotion’s (NOTAP), Technology and Innovation Summit (NTIS 2.0).

Themed ‘From Research to Wealth: Strengthening Innovation, Commercialisation and Technology Sovereignty in Nigeria’, the summit brought together stakeholders from government, academia, research institutions, industry and the financial sector to explore practical pathways for moving innovative ideas from research environments into the marketplace.

Commenting on the summit, Okechukwu Nwoke, Chief Information Officer, Stanbic IBTC holdings, said: “Innovation can deliver greater economic value when promising ideas have the support required to move from research to the marketplace. At Stanbic IBTC, we believe collaboration, skills development and access to finance are important enablers for building sustainable enterprises and supporting Nigeria’s economic growth.”

Speaking during a panel discussion at the summit, Ndukwe Anagha, Head, Information Technology Department, Stanbic IBTC Pension Managers, highlighted Nigeria’s entrepreneurial potential and capacity to develop globally competitive enterprises.

Ndukwe emphasised the need to strengthen academic curricula and equip young Nigerians with skills relevant to emerging technologies. He noted that education and continuous skills development would be essential to advancing Nigeria’s innovation ambitions and preparing young people to participate meaningfully in the evolving digital economy.

In an address delivered on behalf of the Permanent Secretary of the Federal Ministry of Innovation, Science and Technology, Dr. Mukhtar Yawale Muhammed, Mr. Ampe Fut, Director, Technology Acquisition and Adaptation called for stronger mechanisms to connect research with industry, investment and national development priorities.

He said: “Nigeria does not lack ideas, talent or research capacity. Our great challenge is the ability to systematically connect research and innovation outputs to industry, investment, markets and national development priorities”.

Also speaking, Dr. Obiageli Edith Amadiobi, Director-General and Chief Executive Officer of NOTAP, outlined the agency’s efforts to strengthen collaboration between academia and industry. These include the NOTAP-Industry Technology Transfer Fellowship and an initiative focused on upgrading research laboratories.

She explained that involving businesses in defining research priorities could improve the commercial prospects of research outcomes. She also identified product development support, financing and access to markets as important components of a stronger commercialisation ecosystem.

Through its sponsorship and participation in NTIS 2.0, Stanbic IBTC contributed to conversations on the partnerships, capabilities and financing required to transform promising innovations into sustainable enterprises.

The company’s involvement further reflects the Group’s commitment to supporting enterprise development, skills advancement and innovation-led economic growth in Nigeria.

Face of Independence Nigeria Pageant, Hero Awards Set for Oct 24 in Lagos

0

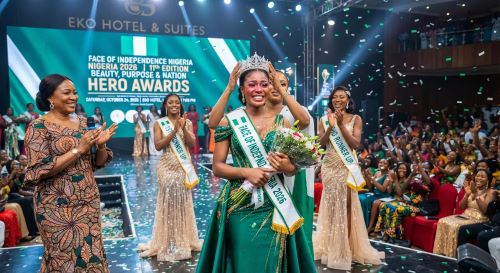
The 11th edition of the Face of Independence Nigeria (FOIN) Beauty Pageant and Hero Awards 2026 will hold on Saturday, October 24, 2026 at Eko Hotel & Suites, Victoria Island, Lagos under the theme: Beauty, Purpose and Nation.

Time is 7.00 pm.

Barrister Catherine Ajije Oloidi, Executive Director of the Pageant said the objective of the show is to build girls who can become leaders, entrepreneurs, advocates, ambassadors and change-makers.

Oloidi said: “We want to create a platform where a contestant can come in as an aspiring queen and leave with greater confidence, knowledge, networks, exposure and opportunities. We also want to use the platform to amplify issues affecting girls, young people and communities, while encouraging our queens to develop advocacy that create measurable social impact. Ultimately, we want the crown to become a tool for purpose and service.”

The pageant promoter said the winner of the pageant will go home with N5 million and represent Nigeria in an international pageant, while her runner ups will earn N2 million and N1 million each.

She described the crown as a responsibility and for the eventual queens to understand that beauty can open a door, but character, knowledge, competence and purpose remain key factors that would keep them in the room or position.

“Face of Independence is not just about beauty, glamour and entertainment. Our identity is deeply connected to Nigeria’s history, effort of our heroes who fought for Nigeria’s independence, patriotism, nation-building and the empowerment of the African girl,” she added.

On the contest, Oloidi emphasised that one factor that stood out was the sense of purpose by the contestants, as all of them came with personal stories and causes that were very inspiring.

“We also saw resilience, confidence, creativity and a strong desire to make an impact. We saw girls who knew so much about Nigeria’s history. Some of them are already building businesses or engaging in community initiatives. We saw contestants who were beautiful, articulate, intelligent, young, vibrant, talented and passionate. Some had backgrounds in entrepreneurship, entertainment, modelling, education, advocacy and other fields.”

She said the main thrust of the pageant is not simply about who is the most beautiful but who is prepared to become the Face of Independence Nigeria.

“Join us on the 24th of October 2024 at Eko Hotels and Suites, Victoria Island, Lagos as we crown the 11th Face of independence Nigeria Beauty Queens and as we honour our heroes with an Independence Hero Award.”

Some of the dignitaries that will receive special recognition awards and honours at the event include: Hon. Mary Alile Idele, PhD, Icon Female Political Leader of the Year Award; Mrs. Sandra Williams Oladele, Democratic Patriot of the Year; Hon. Aisha Ibrahim Baiyee, Excellence in Gender Inclusion and Sustainable Development Award; Amb. Dr. Hadiza Umar (Global MD, Hazdakos) Humanitarian Ambassador of the Year; Amb. Dr. Charles Omini, Human Rights Advocate of the Year and Mrs. Uyime Anietie Adams, Humanitarian Leader of the Year etc.

One of the corporate firms that sponsored the pageant, SAMUELSON Consulting Group, stated that the objective behind the effort is to give back to society in form of Corporate Social Responsibility (CSR), especially for the youth segment of the population.

Mr. Tony Epelle, Managing Consultant & CEO of SAMUELSON said: “We decided to assist in the promotion and sponsorship of FOIN because it highlights the significance of the independence of the country with all our potential for greatness. It also showcases the talents and aspirations of young Nigerians, serves as platform for talent-development and molding, as well as youth empowerment programme.”

How Mobile Banking Makes Everyday Transactions Easier

0

Mobile banking is changing how Nigerians manage money, pay bills and complete everyday financial transactions.

The value goes beyond having a bank on a smartphone. It lies in helping customers complete important banking tasks without allowing those tasks to disrupt work, business, family responsibilities or personal schedules.

A routine visit to a bank branch can take more time than expected. Customers may have to contend with traffic, travel time and queues. For a business owner, this could mean leaving a shop during a busy period. An employee may have to sacrifice a lunch break, while a parent may need to reorganise an already demanding day.

Bank branches remain important for customers who require financial advice, documentation or assistance with complex transactions. However, many routine banking activities can now be completed digitally.

The Fidelity Mobile App allows customers to conduct several transactions within a secure digital environment. These include money transfers, airtime purchases, bill payments, balance enquiries, mini statements, debit card requests and selected cross border payments.

Mobile Banking for Everyday Financial Needs

Financial needs often arise without warning.

A supplier may send an invoice. A relative may require financial support. Airtime may run out during an important call. An electricity bill may become due. A customer may also need to confirm if a transfer has been received.

These are ordinary moments that require quick and convenient banking solutions.

Through the Fidelity Mobile App, customers can initiate transfers and review beneficiary details before authorising payment. They can also purchase airtime, pay supported bills, check account balances and review recent transactions through a mini statement.

These features help customers complete frequent banking tasks without interrupting the rest of their day.

A customer can check an account balance before making a purchase, transfer money after receiving an invoice or review recent transactions before taking a financial decision.

The app also supports debit card requests for eligible customers. A customer can select a relevant account and an available card option, provide delivery details and proceed in line with the applicable issuance and delivery terms.

This allows the customer to begin the debit card request process without first visiting a branch.

More than a Money Transfer App

Many customers download a mobile banking app mainly to transfer money. Some continue to use only that feature even when other useful services are available.

The next phase of digital banking adoption must therefore focus on helping customers understand the broader range of financial needs that mobile applications can address.

A customer who regularly transfers money can also use the Fidelity Mobile App to pay supported bills. A customer reviewing recent transactions may identify an unfamiliar debit earlier. Someone preparing for a trip may begin a debit card request digitally.

Small business owners may also use supported payment options to meet eligible obligations across African markets.

The Fidelity Mobile App provides access to PAPSS for eligible customers. The Pan African Payment and Settlement System (PAPSS) enables cross-border payments to be initiated in Naira, while beneficiaries receive the applicable local currency in their country.

The service can support eligible business payments, school related obligations and family support across available African payment corridors. Transactions remain subject to applicable requirements, charges and terms.

These services position the Fidelity Mobile App as more than a transfer platform. The app provides customers with access to a broader range of everyday banking services from a familiar digital environment. 

Safe Mobile Banking Remains Essential

Speed and convenience are important, but customers also need confidence when using digital banking channels.

Customers should download or update the Fidelity Mobile App only through official application stores. Login details must be protected, while personal identification numbers and one-time passwords should never be shared.

Before approving a transfer, customers should confirm the beneficiary’s name and transaction amount. Service or customer references should also be checked before completing bill payments.

Customers should regularly review account activity and promptly investigate unfamiliar transactions.

A few seconds spent reviewing payment details can prevent a costly mistake. Digital banking should reduce unnecessary effort without reducing customer attention.

The strongest mobile banking experience combines convenience, security and customer control.

Giving Customers More Ways to Bank

Mobile banking does not remove the importance of other banking channels. It gives customers more choice.

A branch may be suitable for one transaction, while a relationship manager may be required for another. USSD can support banking during a low data moment, while the Fidelity Mobile App can handle many routine transactions independently.

The important consideration is that customers should be able to choose a channel that fits their immediate needs.

For Fidelity Bank, the opportunity is to make its digital and physical channels work together as part of one customer relationship.

The value of the Fidelity Mobile App should therefore be measured by the difference it makes in everyday life.

It could be the supplier who receives payment without the business owner leaving the shop. It could be the airtime purchase completed without interrupting an important task. It could also be the balance checked before a decision; the debit card request started without rearranging a schedule or an eligible African payment initiated from a familiar screen.

A banking transaction may take only a few minutes. Completing it from a convenient location can leave customers with more time for the people, businesses and responsibilities that matter.

 By Tolulope Rojaiyes

AXA Mansard Holds 34th AGM in Lagos

0

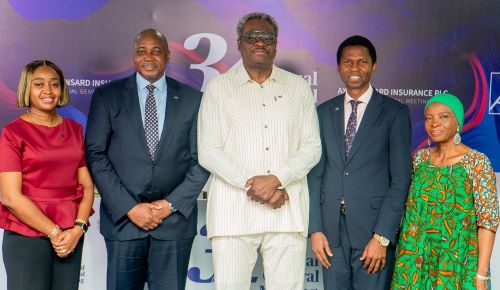
General Counsel/Human Resources Director, AXA Mansard Insurance Plc, Omowunmi Mabel Adewusi (left); Chief Executive Officer, AXA Mansard Insurance Plc, Kunle Ahmed; Chairman, AXA Mansard, Kola Adeshina; Chief Executive Officer, AXA Mansard Health, Tope Adeniyi, and Independent Non-Executive Director, AXA Mansard Insurance, Mrs. Abiola Bada, during AXA Mansard’s 34th Annual General Meeting.

Mutual Benefits Advocates Insurance-Led Resilience at UNILAG Research Conference

0


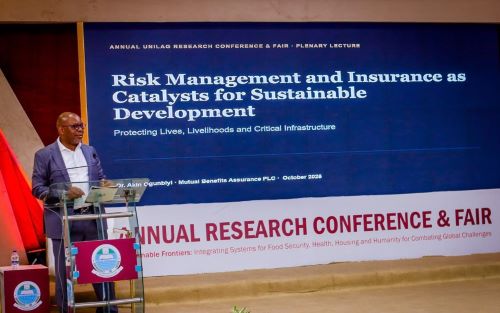
  • MD/CEO, Femi Asenuga, representing Group Chairman Dr. Akin Ogunbiyi, warns that Nigeria’s development gains will keep slipping away unless risk is managed and insured.

Nigeria must integrate risk management and insurance more deliberately into its sustainable development agenda to protect households, businesses, public institutions and critical infrastructure against shocks, the Managing Director/Chief Executive Officer of Mutual Benefits Assurance Plc, Mr. Olufemi Asenuga, has said.

Asenuga made the call while delivering a plenary paper on behalf of the Group Chairman of Mutual Benefits, Dr. Akin Ogunbiyi, at the 19th Annual Research Conference & Fair of the University of Lagos, Lagos.

Titled “Risk Management and Insurance as Catalysts for Sustainable Development: Protecting Lives, Livelihoods and Critical Infrastructure,” the paper examined how insurance can help individuals, businesses and governments withstand financial shocks, preserve development gains and recover from unexpected losses.

“Development is not what a nation builds. Development is what survives,” the presentation declared, emphasising the importance of protecting investments and livelihoods against preventable and unforeseen risks.

Aligning his arguments with the conference’s focus on food security, health, housing and humanity, Asenuga described insurance as an essential component of national development, rather than a peripheral financial service. While risk management helps identify and reduce potential losses, insurance provides financial protection against covered events, enabling households, businesses and public institutions to recover and maintain continuity.

He noted that the United Nations Sustainable Development Goals recognise the importance of resilience and financial protection, particularly Target 1.5, which promotes the resilience of vulnerable populations, and Target 8.10, which encourages access to insurance and other financial services.

The presentation highlighted Nigeria’s growing insurance market but cautioned that rising premiums do not necessarily translate into broader access to protection. Industry figures cited in the paper put gross insurance premiums at approximately ₦2.3 trillion in 2025, up 47 per cent from about ₦1.56 trillion in 2024. However, low insurance penetration continues to leave many households and businesses exposed to financial shocks arising from illness, death, fire, flooding and business interruption.

Asenuga identified low incomes, limited insurance awareness, public distrust, weak enforcement of compulsory insurance, inflation and the largely informal structure of Nigeria’s economy as key barriers to wider insurance adoption.

He stressed that expanding coverage would require affordable and relevant products, transparent policy terms, prompt settlement of valid claims, stronger regulatory enforcement and distribution channels suited to how Nigerians live and earn.

The paper outlined insurance’s contribution across three critical areas of sustainable development. For households, life assurance, health insurance and personal property protection can help prevent unexpected losses from depleting savings, disrupting children’s education or pushing families into poverty.

For businesses, particularly micro, small and medium-sized enterprises, insurance can support recovery and business continuity following covered losses. Agricultural and index-based insurance can also help farmers manage climate-related risks, protect livelihoods and strengthen food security.

At the infrastructure level, construction and engineering insurance can protect projects, while appropriate risk assessments promote safer development. The presentation also highlighted the potential role of insurance and pension funds in financing well-structured infrastructure investments.

To strengthen insurance’s contribution to national development, Asenuga called for coordinated action by insurers, government, regulators, academia and citizens. He urged insurance operators to build public confidence through ethical practices, efficient claims management, transparent communication, relevant products and greater investment in technology and professional capacity.

He also called on government and regulators to enforce existing insurance requirements, protect public assets, strengthen disaster-risk financing and prioritise preventive measures such as effective drainage, sound building standards, fire safety and flood-risk mapping.

Addressing the university community, Asenuga advocated stronger partnerships between academia and the insurance industry through joint research, internships, data sharing and the integration of risk management and insurance literacy across disciplines. He further encouraged citizens to understand their policies, obtain appropriate protection and embrace preventive practices, noting that cooperatives and esusu groups could help expand access to group insurance.

He emphasised that insurance does not replace sound public policy, preventive measures or investment in social infrastructure. Rather, it complements these interventions by helping individuals, businesses and institutions absorb the financial consequences of covered losses without sacrificing the progress they have achieved.

For Mutual Benefits, the message reinforces the importance of positioning insurance as a practical tool for financial resilience, business continuity and long-term security.

As Nigeria pursues its development ambitions, the central challenge, the presentation concluded, is not merely to build more, but to protect the lives, livelihoods and infrastructure that sustain national progress for generations to come.

Mutual Benefits Assurance Plc is one of Nigeria’s leading insurance companies with over 30 years of experience in providing reliable and innovative life and non-life insurance solutions to individuals, families and businesses. Through innovation, customer-centricity and a commitment to financial inclusion, the company continues to deliver value, protection and peace of mind to customers across Nigeria.


Ex-PenOp CEO, Oguche Agudah, Tasks Pension Operators on SCOPE Concept Post- Recapitalisation

0

As pension sector operators continue to race towards meeting the regulator’s recapitalisation requirements with June 30, 2027 as deadline, their attention has been drawn to issues that lie ahead after recapitalisation.

These issues have been summarised in an acronym titled, SCOPE: meaning Scale, Compliance and regulatory awarenesss, Organisational adoption of technology, People strategy and culture and External engagement and differentiation.

Former Chief Executive Officer of Pension Operators Association of Nigeria (PenOp), Mr. Oguche Agudah, stated these while delivering a paper titled: “Post Recapitalisation and Market Dynamics in Nigerian Pension Industry” at the 11th Annual National conference of Nigerian Association of Insurance and Pension Editors (NAIPE) in Lagos recently.

The need for scale, he said, manifested in business combinations witnessed in the pension sector, some of which are the combination between Trust- fund Pensions and Premium Pension and the combination between Leadway and PAL Pension.

Agudah, who is the Founder and Managing Partner of HRISP Partners, highlighted the advantages of these as gaining economies of scale by the various firms involved, increasing complexity of operations, streamlining costs and competing effectively in the market place.

On compliance and regulatory awareness, he noted that pension was the most rejected sector and this has made the regulator to be at the centre of the industry, ensuring that operators adopt sound compliance and culture.

On adoption of technology, he said operators must ask themselves the question on how to leverage technology to make their operations quicker, simble and help them to scale.

According to him, they should also meditate on how to use Artificial Intelligence to compete as well as how to manage cyber security threat.

Agudah highlighted the fact about the on-going recapitalisation exercise in the industry, as PenCom, having mandated all licensed Pension Fund Administrators (PFAs) to raise their minimum capital from N5 billion to N20 billion and one percent more if their Asset Under Management is above N500 billion by June 2027.

Agudah said the second fact about recapitalisation in the pension sector is PenCom mandating all licensed Pension Fund Custodians (PFCs) to raise their minimum capital to N25 billion by June 2027.

He gave reasons for the pension sector recapitalisation as consolidation of the industry, need to shore up pension losses, to create confidence in the sector, to shape the industry for greater activities and to strengthen the industry.

Agudah warned pension sector operators that recapitalisation was not the end of the business but just a piece of the puzzle, pointing out that in addition to the minimum recapitalisation directive, there were other surrounding directives meant to make the industry stronger, more resilient and in line with the developmental needs of the country.

“Beyond recapitalisation, there are guidelines for cross-border pension contribution such as review of investment guidelines to allow for more investments in sectors that promote economic growth, guidelines for agents to deepen personal  pension plan coverage and include minors, guidelines for improved corporate governance of licensed pension fund operators, framework for payment of additional  benefit for retiring civil servants as well as framework for pension compliance certificate and contribution,” he highlighted.

On current pension market dynamics, Agudah said the overview of the entire market shows that the banking sector, insurance sector and investment managers are core owners of the market.

He listed banks which have stakes in the pension sector as Stanbic IBTC Bank which owns Stanbic IBTC Pensions, Access Bank which owns Access ARM Pensions, GTCO which owns GTCO Pension Managers, Fidelity Bank, which owns Fidelity Pension Managers Limited and FCMB which owns FCMB Pensions.

Agudah also highlighted pension institutions owned by insurance firms as Leadway Pension Managers owned by Leadway Group, Crusader Sterling Pensions, Oak Pensions Limited and Veritas Glanvils Pensions.

According to Agudah, those owned by investment groups include Parthian Pensions, Trustfund Pension, CardinalStone Pensions and CitizensPensions.