
A new study from Habitat for Humanity says that housing microfinance can and should become a mainstream offering for financial institutions in Sub-Saharan Africa as they respond to growing housing needs in the region, particularly from poor people.
The business case study, released yesterday, was entitled “Building the Business Case for Housing Microfinance in Sub-Saharan Africa”. It builds on a project carried out over six years in Kenya and Uganda called “Building Assets Unlocking Access”. The project was a partnership between Habitat’s Terwilliger Center for Innovation in Shelter and the Mastercard Foundation. So far, the project has reached over 47,000 households and mobilized more than US$43 million in capital to benefit over 237,000 individuals.
The business case study argues that housing microfinance, small non-mortgage backed loans for short terms, can become a mainstream offering in the market to address growing housing needs in the region, incremental building patterns, and the land tenure realities of low-income households.
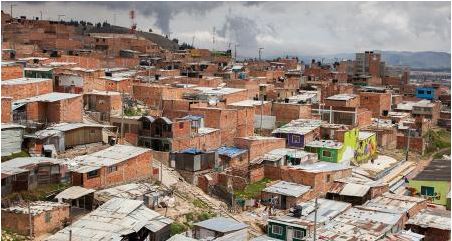
There are an estimated 1.6 billion people in the world living in substandard housing. This figure is climbing, especially as the world becomes more urbanized and people migrate to cities for economic opportunity. In Sub-Saharan Africa, however, as much as 99 percent of people do not have access to formal financing – credit, savings, mortgages – that can let them start building or improving their homes.
Traditionally, they build homes gradually as their resources allow. Developer-built, bank-financed homes are rare in Africa, serving fewer than five percent of households in most countries.
“Solving the housing challenges in Africa will require a massive amount of capital investment and most of that will need to come from the private sector,” said Patrick Kelley, Vice President of Habitat’s Terwilliger Center for Innovation in Shelter. “Financial institutions of all kinds have a role to play, especially those already deeply embedded in communities and who understand people with informal sector livelihoods.”
Habitat’s Terwilliger Center for Innovation in Shelter partnership with the Mastercard Foundation sought to motivate local financial service providers in Kenya and Uganda to develop housing microfinance loans to fund the incremental building process common among low-income households. The results have proven that there is demand for housing microfinance among families or individuals earning as little as US$5 a day who are seeking to build, extend, or renovate their home.
“At the Mastercard Foundation, our focus is on helping economically disadvantaged people, especially young people in Africa, to find opportunities to move themselves, their families and their communities out of poverty,” said Ruth Dueck-Mbeba, Senior Program Manager at the Foundation.
“This project has provided access to appropriate finance for decent housing. We believe that decent housing can provide more than four walls and a roof over one’s head. It offers people hope, dignity, and a place in their communities. This report should help financial service providers to scale these products, which would benefit their enterprises as well as the lives of many poor people in Africa.”
Financial institutions in the region that have ventured into housing microfinance have often reported it to be a popular product with their clients. To understand the demand side factors, the value proposition of these products, the competitive advantage of financial service providers offering it, and the differentiated features that make housing microfinance a strategic product, the business case study surveyed the work of two financial institutions: Kenya Women Microfinance Bank, or KWFT, and Centenary Bank in Uganda.
The study argues, through the lenses of these two institutions in different geographies, that success and profitability of a housing microfinance product relies on a number of factors: connection with the financial service provider’s mission, good marketing, a clear pricing structure, understanding of land tenure realities, an opportunity to attract new clients, and secure long-term capital to fund the expansion of such portfolios.
“Financing incremental housing solutions is a natural step in the progress of greater financial inclusion. Centenary and KWFT are providing a great example of how financial institutions will benefit from understanding their clients and developing products that serve them well,” said Patrick Kelley.