
Understanding How Monthly Pensions Are Paid to Retirees Under the Contributory Pension Scheme (CPS) in Nigeria
The Contributory Pension Scheme (CPS) was introduced in Nigeria as part of the Pension Reform Act of 2004 to ensure sustainable and transparent pension administration.
For retirees under the CPS, understanding how monthly pensions are paid, how pensions are calculated, and how enhancements can be made over time is crucial. Below is a detailed breakdown of these processes.
How Monthly Pensions Are Paid
Retirees under the CPS have two primary options for receiving their monthly pensions: Programmed Withdrawal and Annuity.
Programmed Withdrawal is managed by Pension Fund Administrators (PFAs) and involves structured monthly payments drawn from the retiree’s Retirement Savings Account (RSA). Annuity is a life insurance product purchased from an insurance company, ensuring steady monthly payments for life. The disbursement process depends on the type of benefit being accessed.
For example, Programmed Withdrawal involves monthly payments structured over the retiree’s expected lifespan. The 25% Loss of Job benefit allows employees who lose their jobs and remain unemployed for at least four months to access 25% of their RSA balance.
The 25% Equity Mortgage benefit allows a portion of the RSA to be used as equity contribution for a mortgage, subject to specific conditions.
For Death Benefits, the RSA balance is paid to the designated beneficiaries. All disbursements start with the customer completing the necessary documentation for the benefit type, obtaining approval from PenCom, and then receiving payment.
The National Pension Commission (PenCom) has oversight over all pension disbursements to ensure compliance, transparency, and accuracy.
How Pensions Are Calculated
The calculation of monthly pensions depends on several factors. First, the balance in the RSA is a key determinant, which includes contributions made by both the employee and employer, plus accrued investment returns, forming the total RSA balance at retirement.
Second, life expectancy assumptions are made, and PenCom periodically determines the average life expectancy used in calculating the programmed withdrawal.
Third, retirees can withdraw up to 25% of their RSA balance as a lump sum, provided the remaining balance can fund a reasonable monthly pension. The monthly pension under Programmed Withdrawal is calculated using the formula: Monthly Pension = RSA Balance / Number of Expected Monthly Payments (Life Expectancy in Months).
For example, if a retiree has an RSA balance of ₦10 million and a life expectancy of 20 years (240 months), the monthly pension will be approximately ₦41,667 at the start of the programmed withdrawal. For retirees choosing annuities, the insurance company determines the monthly pension based on the purchase price, interest rates, and life expectancy.
Conditions for the Calculations
Pensions are calculated only when the individual has reached the statutory retirement age of 60 years or has completed 35 years of service. Individuals who retire before the statutory age may access their RSA balance but must meet specific conditions, such as being out of employment for at least four months. In the event of the retiree’s death, the remaining RSA balance is paid to the designated beneficiaries.
Impact of the New National Minimum Wage on Pensions
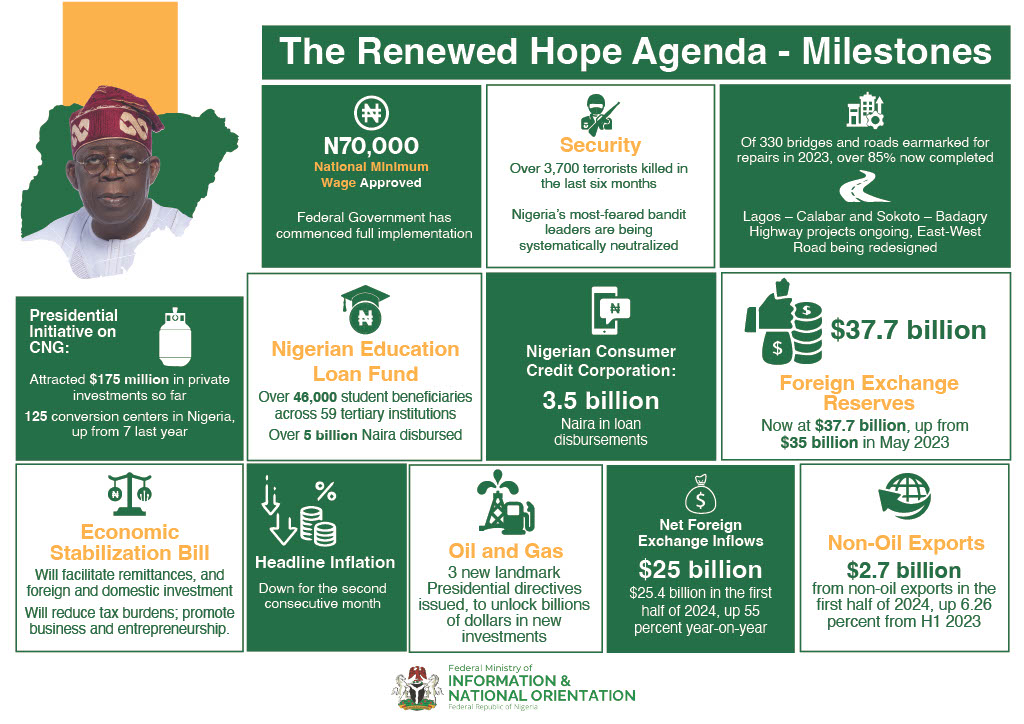
In line with President Bola Ahmed Tinubu’s approval of the new National Minimum Wage Act, which increased the wage from ₦30,000 to ₦70,000, PenCom has updated its regulations. If a retiree’s monthly or quarterly pension is less than ₦23,333.33 (one-third of the current minimum wage), they are allowed to withdraw their RSA balance en bloc or continue receiving their current pensions pending the commencement of the Minimum Pension GuarantePension Fund Administrators (PFAs) must now use ₦70,000 as the basis for processing retirement benefits under the relevant provisions. This adjustment reflects the commitment to ensuring retirees receive adequate support to meet basic living standards.
Understanding Basic Lump-Sum Withdrawals
Retirees can withdraw a portion of their RSA balance as a lump sum, subject to PenCom’s regulations. The lump-sum amount is determined such that the remaining RSA balance can provide a monthly pension of at least 50% of the retiree’s last monthly basic salary. This provides immediate liquidity for retirees to address pressing financial needs, such as settling outstanding debts or making investments. However, taking a larger lump sum reduces the RSA balance available for monthly pensions.
Movement in Fund Unit Prices and Associated Fees
The fund’s unit price fluctuates based on market conditions and the performance of the underlying investments during the period under consideration. The returns for the fund are calculated after deducting audit fees and management fees. Management fees comprise fees charged by the PFA, Pension Fund Custodian (PFC), and PenCom. These fees vary depending on the specific fund and are calculated either on the Net Asset Value (NAV) or as income-based (derived from income generated by the fund during the period), as is the case with Fund IV.
Enhancing Monthly Pensions Over Time
To ensure that retirees receive improved monthly pensions, several measures can be implemented within the CPS.
First, PFAs should adopt robust asset allocation strategies to maximize returns on pension funds, particularly by diversifying investments into infrastructure, real estate, and other high-yield sectors. Second, encouraging voluntary contributions during active employment can significantly boost the RSA balance at retirement.
Third, employers can enhance an employee’s pension beyond the 10% statutory requirement. In addition, lowering fees and charges associated with RSA management will leave more funds available for disbursement to retirees.
Fourth, introducing a mechanism to adjust pensions in line with inflation can maintain retirees’ purchasing power.
Fifth, educating employees about the benefits of making additional voluntary contributions and starting early savings is crucial. Finally, offering incentives for employees who delay retirement allows them to accumulate more savings and reduce the strain on their RSA.
The CPS provides a structured framework for ensuring retirees’ financial security. Understanding how monthly pensions are paid, calculated, and enhanced can help individuals plan effectively for retirement. By implementing measures to boost RSA balances, optimize investment returns, and reduce fees, the CPS can continue to deliver sustainable and improved pensions, providing dignity and financial independence for retirees.