


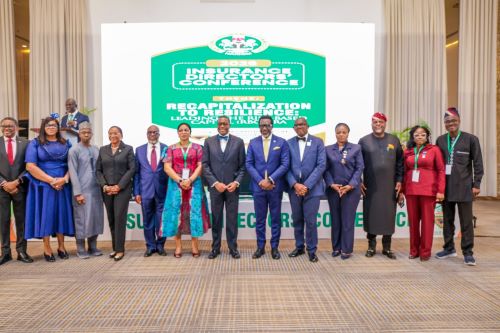


It is my distinct honour to welcome you to the 8th Annual Insurance Directors’ Conference.
I commend the College of Insurance and Financial Management, in collaboration with NAICOM, for sustaining this strategic platform of regulatory dialogue and engagement with Board members.
This year’s theme, “Recapitalisation to Resilience: Leading the Risk-Based Capital Era,” speaks directly to where our industry stands today and where it must go. It is a defining moment.
The recapitalisation exercise has been concluded, and I sincerely commend shareholders, boards and management for the commitment, sacrifices and strategic decisions that made it possible. You have laid a stronger foundation for our industry.
This conference also marks my first formal engagement with you, distinguished Directors, in the post-recapitalisation era. It therefore provides us an important opportunity to collectively reflect on a critical transition: moving from raising capital to building resilience.
Recapitalisation was never the destination; it is the gateway to a more demanding phase — a phase that will be defined not by the size of capital alone, but by how that capital is governed, protected, deployed and aligned with risk.
That is the essence of the Risk-Based Capital era, and that is the leadership responsibility before us today.
THE CHANGING INSURANCE LANDSCAPE
The insurance business has always been about managing uncertainty. However, the nature, scale and interconnectedness of risks confronting insurance institutions are changing at an unprecedented pace.
Climate-related events continue to increase in frequency and severity. Cyber threats are becoming more sophisticated and pervasive. Technological disruptions are reshaping business models and customer expectations. Economic volatility influences investment performance, while geopolitical developments continue to create uncertainties across global supply chains and financial markets.
In addition, demographic changes, emerging technologies, evolving regulatory expectations and changing consumer behaviour are creating new opportunities as well as new vulnerabilities.
Policyholders are increasingly demanding greater transparency, faster service delivery, personalised products, enhanced digital experiences and, above all, confidence that insurers will honour their obligations when claims arise.
These developments require insurance institutions to move beyond traditional approaches to business management and risk supervision. Insurance companies must become more responsive, innovative, technologically enabled and financially resilient.
Against this backdrop, insurance regulators across the world are rethinking traditional solvency frameworks and adopting risk-sensitive approaches that better reflect the realities of modern insurance operations.
Nigeria cannot afford to be a spectator in this transformation.
As regulators, our responsibility extends beyond ensuring compliance with statutory requirements. We must ensure that insurance institutions remain financially sound, operationally resilient, well-governed and capable of honouring their obligations to policyholders under different economic and operating conditions.
This is the fundamental principle underpinning the transition towards Risk-Based Capital.
FROM RECAPITALISATION TO RESILIENCE: THE NEXT PHASE
The critical question before us is no longer simply whether insurance institutions have met the prescribed capital requirements. It is whether they can translate their strengthened capital positions into improved underwriting capacity, stronger risk management, better claims-paying ability, operational efficiency and sustainable growth.
However, these opportunities must be pursued within a framework of prudence and sound corporate governance.
Boards must therefore pay particular attention to the quality of capital, the manner in which it is deployed, the risks it supports and the returns it generates.
Let me reiterate that a well-capitalised institution is not necessarily a resilient institution. Experience across financial markets has shown that institutions with substantial financial resources can still fail due to poor governance, weak internal controls, ineffective risk management, inappropriate investments and inadequate board oversight.
True resilience is the ability of an institution to anticipate risks, absorb shocks, adapt to changing circumstances, recover from disruptions and continue delivering value to stakeholders.
THE REAL TEST OF RECAPITALISATION
Permit me to place particular emphasis on corporate governance, because I consider it one of the most important determinants of the success of our post-recapitalisation industry.
As earlier stated, the strength of an insurance institution cannot be measured by its capital base alone. It must also be reflected in the quality of its board oversight, the integrity of its leadership, the effectiveness of its internal controls and the discipline with which it conducts its business.
As directors, you occupy positions of significant trust and responsibility. Your mandate goes beyond representing shareholder interests or attending board meetings. You are entrusted with safeguarding institutional integrity, providing strategic direction and ensuring that the companies you govern remain financially sound and operationally sustainable.
The era in which boards functioned primarily as recipients of management reports must give way to a more active and challenging approach to effective board oversight.
Effective boards must ask difficult questions, interrogate management assumptions, challenge strategies where necessary and ensure that decisions are supported by adequate information and sound judgement.
In the post-recapitalisation environment, I expect boards to demonstrate stronger ownership of the following responsibilities:
- Strategic leadership and oversight. Boards must ensure that institutional strategies are realistic, sustainable and consistent with the company’s capital position, business model and risk appetite. Growth ambitions must be supported by adequate financial resources, operational capabilities and appropriate risk management arrangements.
- Capital stewardship. Directors must understand how capital is generated, allocated, invested and protected. They must ensure that capital is not eroded through poor underwriting, excessive operating costs, inappropriate investments or uncontrolled expansion. Capital management must be a continuous board responsibility and not merely a matter for the finance department or an occasional regulatory review.
- Effective risk governance. Boards must establish and periodically review appropriate risk appetite frameworks, ensuring that management operates within approved limits. They must pay particular attention to underwriting concentrations, reinsurance arrangements, investment exposures, liquidity, credit risk, operational risks, technology-related threats and other material vulnerabilities.
- Management accountability. Boards must establish clear performance expectations for executive management and ensure that management decisions are consistent with approved strategies and policies. The relationship between boards and management must be characterised by constructive engagement, clear accountability and appropriate separation of responsibilities.
- Internal control and assurance. Internal audit, compliance, risk management and actuarial functions must be sufficiently resourced, competent and empowered to discharge their responsibilities effectively. These functions must have appropriate access to the board and relevant board committees, with sufficient independence to report weaknesses without fear of interference or retaliation.
- Board composition and effectiveness. The composition of boards must reflect the growing complexity of the business. Boards must collectively possess the necessary mix of insurance, financial, actuarial, legal, investment, technology, risk management and other relevant expertise. Directors must also commit to continuous professional development to remain abreast of emerging risks, regulatory developments and changing business models.
Let me particularly emphasise that board membership is not an honorary appointment. It is a position of trust that carries significant fiduciary, professional and regulatory obligations.
SHAREHOLDER EXPECTATIONS, BOARD INDEPENDENCE AND MANAGEMENT ACCOUNTABILITY
Another important consideration in the post-recapitalisation era is the relationship between shareholders, boards and executive management.
The successful mobilisation of additional capital naturally creates expectations among investors and shareholders regarding returns, growth and institutional performance. These expectations are legitimate.
However, they must be balanced against the fundamental obligations of an insurance institution to its policyholders, creditors, employees, regulators and the wider public.
Shareholder interests must not override prudential considerations, undermine board independence or encourage management to pursue unsustainable business strategies.
Boards must be able to exercise independent judgement, even where their decisions may not align with the immediate expectations of particular shareholders.
Similarly, executive management must be held accountable for the prudent use of institutional resources, business performance, regulatory compliance and the implementation of board-approved strategies.
A NEW PRUDENTIAL DISCIPLINE
As we transition into the Risk-Based Capital regime, it is important to appreciate the complementary but distinct roles of the Minimum Capital Requirement (MCR) and Risk-Based Capital (RBC).
The Minimum Capital Requirement establishes the minimum capital threshold that an insurance institution must maintain to undertake its licensed business. It provides a fundamental prudential safeguard and establishes a baseline for regulatory compliance.
Risk-Based Capital takes the assessment further by considering the risks assumed by an institution and the capital required to support those risks.
This distinction is fundamental to the new supervisory philosophy. An institution may satisfy its minimum capital requirement but still have insufficient capital relative to the nature, scale and complexity of its risk exposures.
WHAT SHOULD THE INDUSTRY EXPECT FROM THE REGULATOR GOING FORWARD?
The transition to Risk-Based Capital will inevitably require adjustments in the way insurance institutions are managed and supervised.
NAICOM’s supervisory approach will increasingly emphasise the quality of capital, the adequacy of risk management frameworks, governance effectiveness, institutional resilience and the capacity of companies to meet their obligations to policyholders.
We expect insurance institutions to demonstrate a clear understanding of their risk exposures and maintain appropriate systems for identifying, measuring, monitoring and managing those risks.
There will also be greater emphasis on the quality and reliability of regulatory returns, financial reporting, actuarial assessments and disclosures.
We expect boards and management to ensure that information submitted to the Commission is accurate, complete, timely and reflective of the institution’s actual financial and operational position.
Institutions must also strengthen their internal assurance arrangements and ensure that material weaknesses are identified, escalated and addressed promptly.
Let me make it clear that successful recapitalisation does not confer permanent immunity from regulatory scrutiny. Capital adequacy is a continuous responsibility. Institutions must remain financially sound and compliant throughout their operations.
Similarly, regulatory engagement should not be regarded as an exercise that begins and ends with the submission of returns or the conduct of on-site examinations.
We expect institutions to maintain open, transparent and constructive engagement with the Commission, particularly where material developments or emerging vulnerabilities may affect their financial condition or ability to meet policyholder obligations.
IMPLICATIONS OF RECAPITALISATION FOR THE NIGERIAN ECONOMY
The significance of recapitalisation extends far beyond the balance sheets of individual insurance companies. It has important implications for the Nigerian economy.
A stronger insurance industry is better positioned to support national economic development.
Our infrastructure, energy, manufacturing, agriculture, construction and other strategic sectors require a strong and dependable insurance industry capable of supporting investments and managing increasingly complex risks.
There is also an important opportunity to deepen domestic risk-retention capacity and reduce dependence on foreign insurance markets,
A stronger insurance industry can also become a more significant source of long-term institutional investment, contributing to the development of Nigeria’s financial markets and productive sectors.
Furthermore, increased institutional capacity provides opportunities to deepen insurance penetration, expand access to affordable insurance products and support financial inclusion.
The relationship between insurance and economic development must therefore become more deliberate.
However, these benefits will not materialise automatically. The insurance industry must demonstrate greater willingness to support productive economic activities, develop innovative products, improve service delivery and build public confidence through prompt and fair claims settlement.
I therefore challenge insurance institutions to translate their strengthened capital positions into greater economic relevance.
We must build an industry that is not only financially stronger but also more visible, accessible and impactful in the lives of Nigerians.
POLICYHOLDER PROTECTION, MARKET CONDUCT AND PUBLIC CONFIDENCE
At the centre of the insurance business is a promise: the promise to provide financial protection when an insured event occurs.
The public does not measure the strength of an insurance company by the size of its capital alone. Ultimately, policyholders judge institutions by their willingness and ability to honour their contractual obligations.
This makes claims settlement one of the most important determinants of public confidence in the industry.
I therefore urge boards to place policyholder protection at the centre of their institutional strategies.
FIT AND PROPER REQUIREMENTS: GOVERNANCE BEGINS WITH PEOPLE
No discussion of corporate governance would be complete without addressing the importance of Fit and Proper requirements.
For regulators, governance begins with people. The Fit and Proper Framework is therefore far more than a regulatory requirement; it is a fundamental governance safeguard.
It ensures that directors, chief executives and key management personnel possess the qualifications, experience, competence, reputation, financial soundness and ethical standing necessary to discharge their responsibilities effectively.
Appointments to boards and senior management positions should never be based solely on status, familiarity, influence or relationships. They must be driven by competence, character, capability and commitment to institutional success.
In an increasingly complex financial environment, board composition must reflect the range of expertise required to govern modern insurance institutions.
Importantly, responsibility for upholding these standards does not rest solely with the regulator. Boards themselves must continuously assess, monitor, document and verify compliance with fit-and-proper requirements throughout the tenure of directors and senior executives.
A CALL TO LEADERSHIP: BUILDING A STRONGER INDUSTRY
The post-recapitalisation era presents a unique opportunity for the Nigerian insurance industry.
It is an opportunity to strengthen financial soundness, deepen public confidence, enhance investor trust, elevate governance standards and position our industry as a stronger contributor to national economic growth and financial inclusion.
However, opportunities do not automatically translate into outcomes.
Progress requires leadership. Transformation requires commitment. Resilience requires discipline and deliberate action.
As we move into this new phase, I would like to leave you with a number of important questions for reflection:
- Having successfully recapitalised, are our institutions genuinely stronger, or have we merely satisfied a regulatory threshold?
- Are our boards adequately equipped to understand and challenge the risks being undertaken by our institutions?
- Are we deploying our strengthened capital prudently and strategically?
- Have we established governance structures that can prevent the weaknesses and failures that have historically undermined financial institutions?
- How will we ensure that increased capital translates into improved underwriting capacity, better claims settlement and stronger policyholder confidence?
- And, perhaps most importantly, how will the stronger insurance industry contribute more meaningfully to Nigeria’s economic development?
These are not merely regulatory questions. They are questions of leadership, institutional responsibility and the future of our industry.
To all directors gathered here today, I wish to reiterate that your responsibilities have increased.
You are not merely directors of insurance companies. You are custodians of policyholders’ trust. You are stewards of shareholders’ investments. You are guardians of institutional integrity. You are champions of sound governance. You are architects of corporate resilience. And above all, you are stewards of the future of the Nigerian insurance industry.
The decisions taken in your boardrooms today will determine whether the gains of recapitalisation are sustained, whether our institutions become more competitive, and whether the industry earns the confidence and trust of Nigerians.
Let us ensure that the post-recapitalisation era is remembered not merely as a period when insurance companies raised more capital, but as the period when the Nigerian insurance industry fundamentally transformed its governance, strengthened its institutions and became more relevant to national development.
On behalf of the National Insurance Commission, I wish you all fruitful deliberations and a highly successful conference.
Thank you for your attention.
Olusegun Ayo Omosehin
Commissioner for Insurance/Chief Executive
National Insurance Commission (NAICOM)