


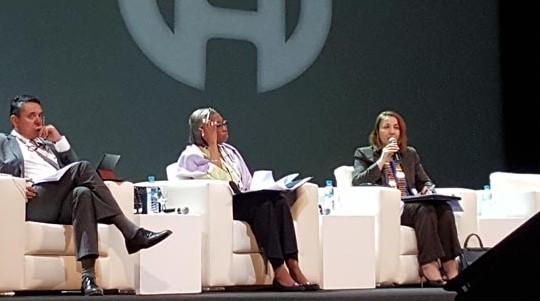


The African Insurance Organisation (AIO) has launched its first Africa Insurance Barometer at the 43rd AIO Conference & General Assembly in Marrakech, Morocco.
According to the survey, which is based on in-depth interviews with 28 senior executives from regional and international insurers, reinsurers and brokers, the African insurance markets benefited to some extent from the economic boom of the past years. Regulation improved and insurance gained in relevance.
However, insurance penetration and share of insurance premium as a percentage of Gross Domestic Product (GDP) are still exceptionally low.
Going forward, the majority of the executives polled predict that Africa’s insurance markets with annual premium of US$ 69 billion will grow in line with the continent’s GDP or even faster.
”The AIO aims to contribute to advancing Africa’s insurance markets for the benefit of our member’s organisations and also the overall economies and societies, in which we operate,” says Prisca Soares, Secretary General of the African Insurance Organisation.
“The Africa Insurance Barometer offers a succinct summary of the key regional insurance market data and highlights the relevant trends and developments of our industry. We thereby provide greater transparency of the African insurance markets, while facilitating and encouraging an informed dialogue about its opportunities and challenges.”
The growth and expansion of Africa’s insurance markets is closely linked to the economic boom that the region experienced in recent years. While investments into infrastructure and construction grew and the affluence of Africa’s population improved, insurance’s relevance increased.
The insurance market’s robustness improved significantly, partly due to tighter regulation and also enhanced distribution of insurance products through bancassurance and mobile phone distribution. Insurance penetration remained exceptionally low.
In some countries it only amounts to less than 1% – well below the global emerging market average of 2.7% in 2014, demonstrating the enormous growth potential within the industry.
But, according to the executives, Africa’s insurance markets still suffer from a shortage of skilled and experienced insurance professionals and a lack of awareness of the benefits of insurance. In addition, excessive competition and insufficient product differentiation hamper the market’s growth potential. Declining rates will affect profitability Africa’s insurance industry is expected to grow.
The insurance executives polled hope for more investments in infrastructure and that further personal lines will become compulsory. Micro insurance is seen as a driver for growth, although it is frequently perceived as insufficiently regulated.
At the same time, rates are coming down due to excess risk capacity in the market. Africa’s insurance markets are perceived as diverse and fragmented. Regulation is seen as inadequate because under-capitalised companies are still thriving, while competing on a price rather than service or quality.
Cross-border business suffers from a lack of regulatory harmonisation. Executives therefore demand closer cooperation between regulators, often citing the CIMA, the Inter African Conference of Insurance Markets, as an example of a successful regional collaboration.
About African Insurance Organisation
Established in 1972 in Mauritius, the African Insurance Organisation (AIO) is a non-governmental organisation recognised by many African governments.
Following the headquarter’s agreement with the Government of Cameroon, the Permanent Secretariat of the AIO was set up in Douala.
The AIO pursues the objective of developing a healthy insurance and reinsurance industry in Africa and to promote inter-African co-operation in insurance.
Currently, the AIO has 371 members, 363 of them from 47 countries in Africa and 13 associate international members from 7 countries.