




By Elvis Eromosele
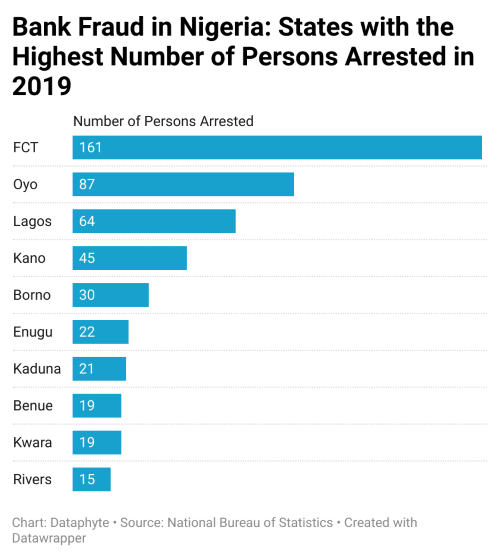
The financial sector is the backbone of any economy, driving transactions, investment, and growth. In Nigeria, the financial sector is under siege.
The recent report from the Financial Institutions Training Centre (FITC) confirms this. The report reveals a shocking escalation in fraudulent activities, leaving banks and customers vulnerable in the first nine months of 2024.
This rising tide of financial fraud raises critical questions: Why is fraud surging, and what can be done to stem the tide?
The FITC Fraud and Forgery Report for Q3 2024 paints a grim picture. Fraud cases reported by Nigerian banks jumped by an alarming 65 per cent from 11,532 in Q2 to 19,007 in Q3. The monetary figures are equally disturbing. In Q3, fraudsters attempted to steal an eye-watering N115.9 billion—more than double the N56.6 billion recorded in the previous quarter.
While the actual losses in Q3 were curbed at N10.1 billion—a significant drop from N42.8 billion in Q2—this still marks a troubling year. In the first nine months of 2024, Nigerian banks lost an estimated N53.4 billion to fraud, a steep increase from the N9.4 billion lost in the entire 2023.
The report attributes this surge to the increasing digitisation of financial transactions, which, while enhancing convenience, has also provided fraudsters with a wider playing field. It is now clear that as banks race to adopt advanced technologies, they must contend with an evolving landscape of cyber threats.
We’ll need to look closer to understand the numbers. For instance, despite the surge in fraudulent attempts, the losses incurred have decreased significantly in Q3, indicating improved detection and prevention mechanisms by banks.
In addition, the N53.4 billion lost so far in 2024 dwarfs the N9.4 billion lost in 2023, underscoring an urgent need for strengthened fraud prevention strategies.
Besides, the report indicates that fraud is escalating across all platforms, with digital transactions emerging as a significant area of concern. This is not surprising, for as more Nigerians adopt online banking, the potential for cybercrime has grown exponentially.
This trend is driven by several factors. Many banks lack advanced cybersecurity measures capable of countering sophisticated fraud schemes.
Internal collusion remains a significant issue, with some bank employees aiding fraudsters. Moreover, a lack of public awareness about basic cybersecurity practices makes customers vulnerable to scams like phishing. Regulatory gaps further compound the problem, as the speed at which fraud tactics evolve often outpaces existing measures.
Notwithstanding the challenges, there is a glimmer of hope. The reduction in losses in Q3 suggests that banks are improving their detection and prevention mechanisms. However, this progress needs to be scaled up and sustained. Addressing the fraud epidemic will require concerted efforts from all stakeholders, including financial institutions, regulators, and customers.
First, banks must strengthen their cybersecurity infrastructure. Advanced fraud detection systems powered by artificial intelligence and machine learning can help identify unusual transaction patterns and flag them before significant losses occur.
Second, employee training and accountability must be prioritised. Bank staff should be regularly trained on fraud prevention techniques, while stricter penalties and internal monitoring systems can help deter insider threats.
Third, public awareness campaigns are essential. Customers need to be educated about protecting their financial information and recognising potential scams. Simple actions, such as not sharing sensitive banking details or ignoring unsolicited messages, can make a significant difference.
Furthermore, collaboration is another key element. Banks and regulatory bodies should share data on emerging fraud trends, creating a unified database to help institutions stay ahead of criminal tactics. Regulatory frameworks also need to evolve, ensuring stricter penalties for fraud and keeping pace with technological advancements.
The FITC report serves as a wake-up call for stakeholders in Nigeria’s financial sector. While commendable progress has been made in reducing actual losses, the overall increase in fraud attempts underscores the need for a more proactive approach. This is not just a banking issue—it is a national economic threat.
It is clear that Nigeria can turn the tide against financial fraud by prioritising cybersecurity, fostering collaboration, and empowering citizens with knowledge. For banks, customers, and regulators alike, the message is clear: the time to act is now.
Eromosele, a corporate communication professional writes via: elviseroms@gmail.com