


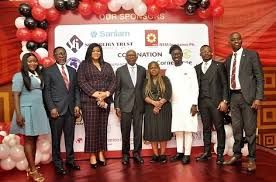


Dr. Akeem Oyewale, the Chief Executive Officer of Marble Capital Limited, who delivered the keynote paper at the recent BusinessToday Annual Conference in Lagos said a financially empowered youth population boosts national savings and investments, just as higher insurance adoption reduces reliance on government social support, creating a more sustainable economy.
The theme of the conference was “Banking on the Future: Youths, Pension and Insurance Penetration.”
Oyewale lamented however that despite the growing youth population, insurance adoption remains alarmingly low, with Nigeria’s insurance penetration at just 0.5% of GDP, with minimal youth engagement.
“While the global average stands at 6.80%, Nigeria’s rate is significantly lower, suggesting that the country’s insurance sector is underdeveloped. Even in the African context, Nigeria’s penetration rate lags far behind leaders like South Africa (11.54%) and Namibia (7.41%).”
In his goodwill message, Mr. Segun Omosehin, the Commissioner for Insurance and CEO at NAICOM said the Commission is focused on driving innovation and expand youth penetration in the insurance sector in Nigeria.
“As the future depends on how we engage and equip our youth, it’s essential to prioritise their exposure and relevance in the financial sector. To achieve this, the Commission is focusing on building trust and driving innovation to cater to the evolving needs of our growing young population. By that, we encourage the insurance industry to ensure that insurance products and services are tailored to meet the unique requirements of younger generations, promoting financial inclusion, stability and greater adoption of digital insurance solutions.”
He said by emphasising youth engagement and promoting financial literacy, there is a huge opportunity to unlock the potential for growth and development in the insurance sector. This he added, will in turn, contribute to the overall economic prosperity of Nigeria, as the insurance industry plays a vital role in mobilising long-term savings, financing infrastructure projects and promoting risk management.
“As a Commission, we are committed to building trust and driving innovation which will pave the way for a more inclusive and sustainable financial system, where the needs of the young generation are at the forefront.”
He said to secure the financial future of young people, stakeholders must rethink engagement strategies by offering youth-friendly financial products to meet the unique needs of young people, strengthening financial education by introducing targeted literacy programs, leverage workplace initiatives to promote insurance participation.
“Insurance services are key initiatives that when made youth-friendly, can change the face of capital formation and wealth dynamics in Nigeria.”